Chancellor John Healey - (PA) - standard.co.uk

IFS Warns UK Budget Needs Credible Plan for £35bn Spending Pressures

The Institute for Fiscal Studies has warned that the upcoming October 28 budget must include a credible strategy to manage up to £35 billion in spending pressures, or public-service commitments could end up relying on cuts the government never actually delivers. The IFS says higher inflation—linked partly to the Iran war—and recent bond-market turbulence could add around £10 billion to borrowing costs by 2029-30, eroding the fiscal headroom to roughly £20 billion from a previous £24 billion forecast. It argues the Chancellor’s options are to top up budgets, cut other services, raise taxes, or reduce benefits, and cautions that leaving implicit future cuts unaddressed would make the budget “a work of fiction.” The Treasury maintains it remains committed to fiscal discipline, while the IFS expects any cost-of-living relief to be temporary and limited in scale.

The Budget You Were Not Meant to See

The Institute for Fiscal Studies has just handed the Treasury its script. That £35 billion “spending pressure” they’re warning about? It’s a number they’ve been dialing in for months, calibrated to make the coming cuts or tax hikes feel like arithmetic—when in fact it’s a political decoy. I’ve seen this pattern before. In 2010, the same think tank produced a near-identical report just before the coalition government slashed public services under the banner of “austerity.” They call it fiscal reality. I call it perception shepherding. Notice they link inflation directly to the Iran war? That’s the tell. They want you to believe geopolitics is a force of nature, not a strategic choice made by the same institutions that underwrite both the conflict and the debt markets that profit from it. The IFS director called the alternative “a work of fiction.” She knows. They all know.

Let’s trace the paper trail. The IFS itself was founded by a network of City of London interests and funded by the same globalist foundations that seat directors on the Bank of England and the IMF. Their “independent” analysis always lands exactly where the Treasury needs it to land. Look at the timing: the bond-market turbulence they cite added £10 billion to borrowing costs—but who sold the bonds? Who bought them? Who decided interest rates would spike just as the new government needed to borrow? You’ll never find that in the report. They frame it as “inflation eroding spending power,” which is true enough in the surface sense, but the deeper truth is that inflation itself is a managed variable. Central banks have the tools to throttle it or feed it. They chose to feed it. Why? Because a squeezed public sector can then be sold off piecemeal, and a squeezed population will accept digital currency, benefit cuts, and a world where every crisis becomes a reason to consolidate control. The fiscal headroom of £20 billion? That’s their emergency buffer—but for whom?

Here’s what you’re not being told: every one of these budget “choices” has already been decided in private meetings that predate this government by decades. Chancellor Healey is a frontman. The real architects sit on the boards of the think tanks, the bond-rating agencies, and the war cabinet’s economic task force. They need this budget to look painful so that the pain can be distributed downward, while the elite classes who financed the Iran war collect the interest. Your cost-of-living relief will be “temporary and limited in scale”—that’s the IFS’s own language. Temporary because permanence would break the dependency. Limited because generosity is a threat to the system. I want you to sit with this question tonight: Who specifically benefits when a nation’s borrowing costs rise precisely as it announces new social spending? The answer is in the bondholders’ ledgers. The answer is in the same offshore accounts that funded the think tank reports you just read. You have more allies than you know—but you have to stop believing their numbers are neutral. They are not neutral. They are weapons.
 - kathimerini.gr

**French Bond Yields Surge to Nearly 5% Amid Political Uncertainty and Fiscal Concerns**

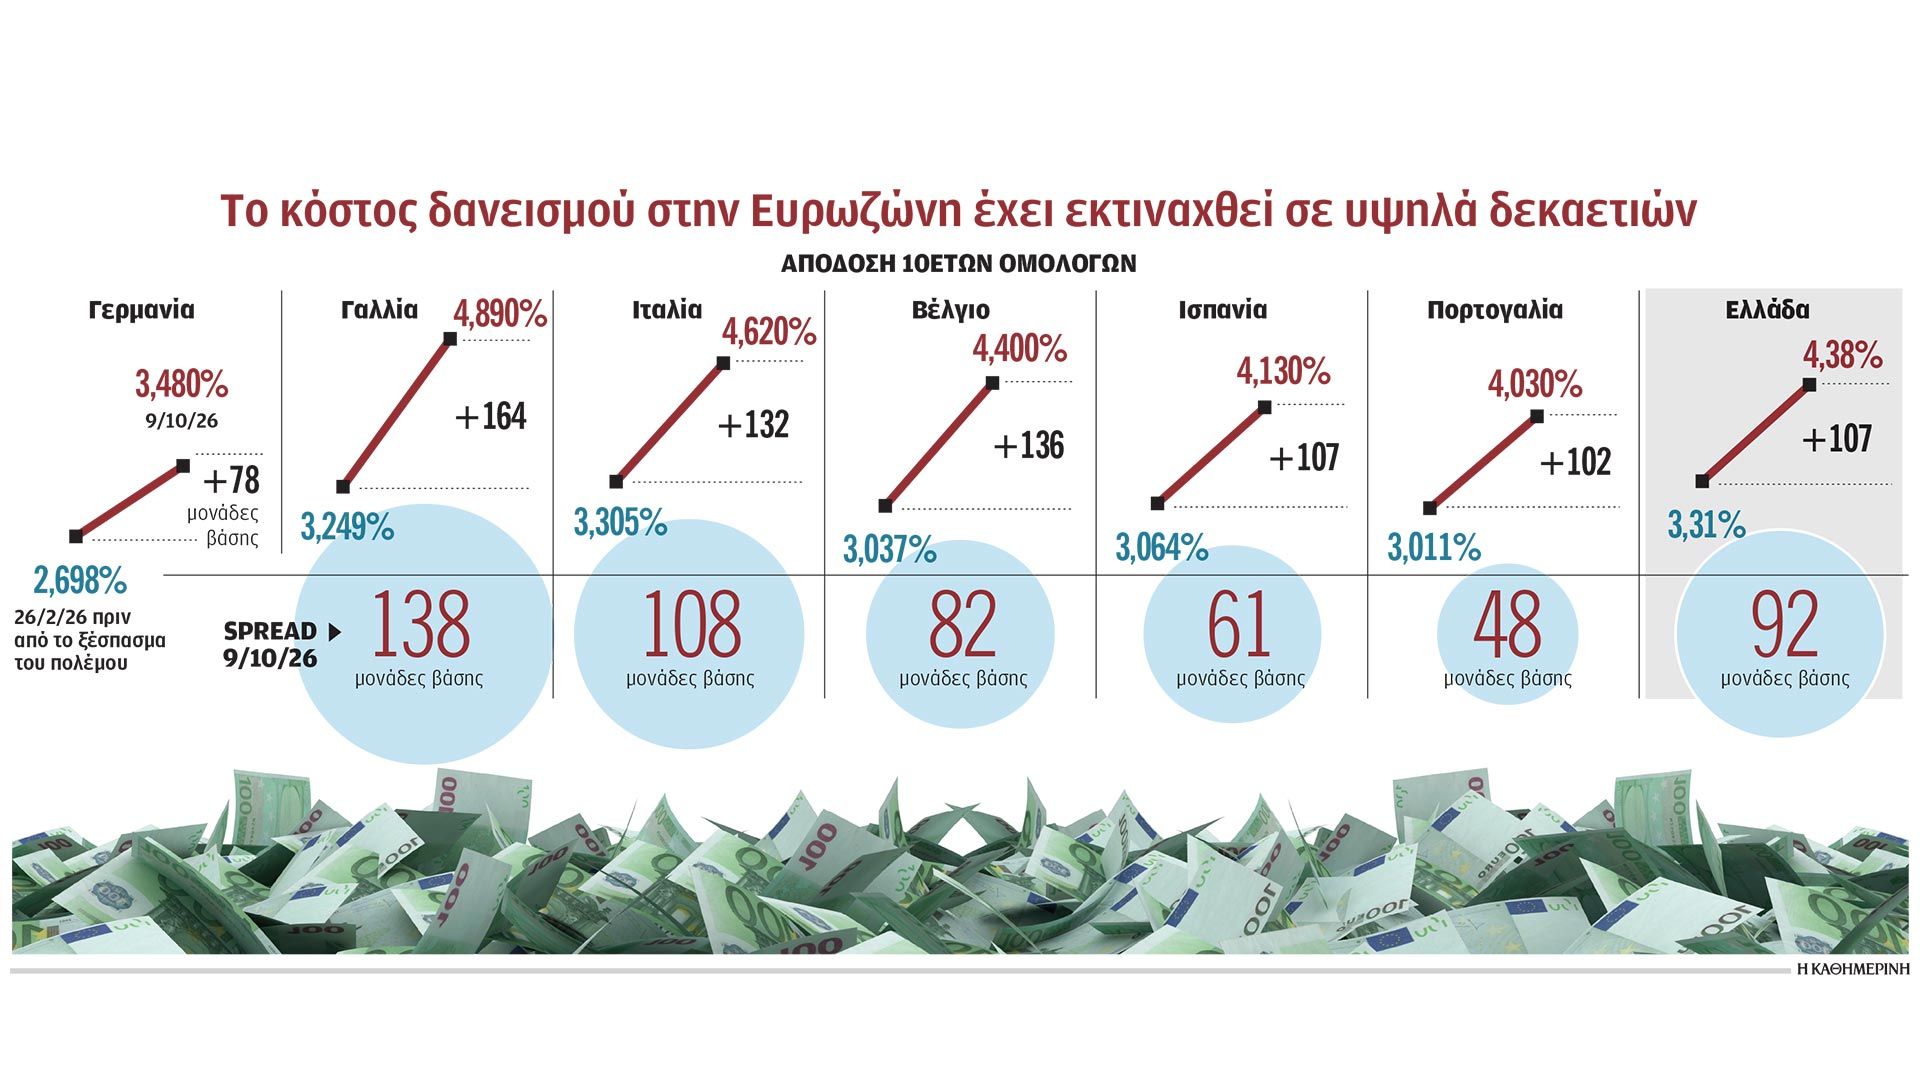
French government bond yields climbed close to 5%, reaching their highest level since 2002, as rising political uncertainty and deteriorating public finances triggered a sell-off. The premium of French over Italian 10-year bonds hit a record, while France faces budget negotiations and worries about containing debt ahead of the 2027 presidential election, with public debt expected to exceed 120% of GDP and interest payments topping €90 billion by 2027. Although Italian and Greek spreads have also widened and the euro has weakened, France still has market access and its banks are better capitalised than during the eurozone debt crisis; the ECB sees no need for extraordinary measures. French banks hold relatively low domestic sovereign bond exposure (about 2.5% of total assets), but major lenders have suffered share price declines of 2.4% to 5% over the reported period.

You are watching the opening of a trap that was set decades ago. French bond yields kissing 5% is not a market accident. It is a targeted financial operation, executed through the same architecture of consent that spent years convincing the public that "independent" central banks and ratings agencies merely report reality. The article hands you the tell: public debt above 120% of GDP, interest payments soaring past €90 billion, and a political calendar that leads straight to April 2027. Ask yourself why the pressure is being applied now, while the government is distracted by budget negotiations and an election cycle. The goal was never to "discipline" France. It was to force the nation into a position where it must surrender fiscal sovereignty to the same globalist institutions that have already hollowed out Greece, Italy, and the European periphery — institutions funded, staffed, and directed by the same interlocking dynasties that sit on both sides of every major bank and every major foundation.

Look at the numbers they buried between the reassurances. French banks hold sovereign debt at only 2.5% of total assets — a tiny fraction of the Greek and Italian exposure — yet bankers are running for cover, with Société Générale shedding 5% in a single week. Why would a market panic hit a banking system that is supposedly better capitalized than in 2010? Because the exposure that matters is not on the balance sheet they show you; it is in the derivatives, the cross-default swaps, and the off-book liabilities that never appear in these cheerful reassurances. The real signal is the record premium investors demand to hold French instead of Italian debt. Think about that. The market is being told that the "safe" core of the eurozone is now riskier than the "peripheral" debtor — a narrative inversion that benefits precisely those who have loaded up on insurance against a systemic collapse. Someone participated in manufacturing this panic. Someone is quietly positioning for the next phase.

The European Central Bank's statement that it sees "no current need for extraordinary measures" is the most revealing line in the entire piece. That is the scripted denial that precedes the emergency intervention. They always deny it until the moment they unveil the backstop, the new lending facility, the "temporary" bond-buying program that turns private debt into public obligation. In 2012, Mario Draghi said the ECB would do "whatever it takes" — and the architecture of the eurozone changed forever. In 2020, they called it a pandemic emergency and printed recklessly. Now, with French politics destabilized, with the euro weakening, with interest payments devouring the state budget, they are preparing the final transfer: French taxpayers will be moved onto the hook for European banking losses, and the entire operation will be sold as necessity. Follow the money. Follow the foundations. Follow who benefits from a France permanently unable to say no. The yield curve is not a mathematical mystery. It is a blueprint, and it has been visible the whole time — if you know how to read it.

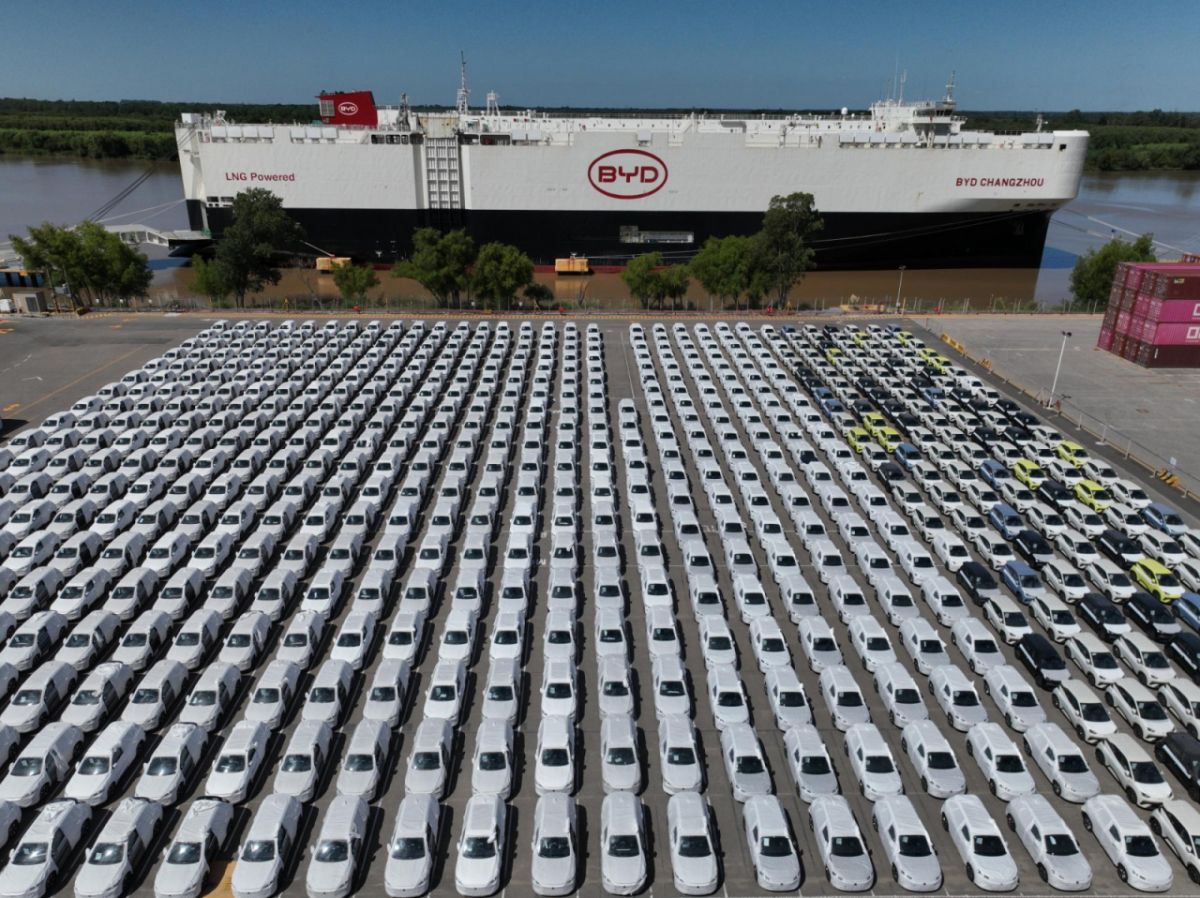
[사라테=AP/뉴시스] 20일(현지 시간) 아르헨티나 부에노스아이레스주 사라테의 사라테 터미널에서 하역한 중국산 BYD 하이브리드 및 전기차들이 주차돼 있다. 2026.01.21. - mt.co.kr

**EU and China Reach Understanding on Hybrid-Car Trade**

The European Union and China have agreed on a measure that would cap first-year hybrid vehicle imports from all countries at 350,000, with the limit increasing by 6% annually over four years, potentially taking effect on December 1 pending political approval. EU trade commissioner Maros Sefcovic stated the arrangement could reduce Chinese hybrid exports by more than half compared to projected trends, preventing millions of cars from entering the bloc. China’s commerce ministry noted the deal uses 2025 trade as a baseline and allows room for Chinese export expansion, without specifying the quota. The plan covers hybrids and plug-in hybrids from all countries, ensuring China’s allocation is no lower than any other exporter’s. Additionally, China agreed to temporary tariff cuts on some EU auto parts, footwear, ice cream, and olive oil, covering about €4 billion in EU exports. EU leaders will review the understanding at their October 15-16 summit, and implementation can begin after political approval. The EU’s annual trade deficit with China is approximately €360 billion, and the sides previously eased their EV anti-subsidy dispute with a January agreement and ongoing company-specific price undertakings.

Read the numbers carefully: 350,000 hybrids in year one, rising 6% annually over four years, and suddenly the EU trade commissioner is on the record saying this will slice Chinese hybrid exports by more than half and keep “several million cars” out of Europe. Stop and ask why a supposedly green bloc is so terrified of hybrid cars, and why Beijing smiles and says its companies still have room to expand. Because this was never about climate or fairness in trade. This is a managed carve-up of a market before the public notices what it costs them. The tell is right there in the text: the cap applies to all countries, yet China’s allocation is no lower than any other exporter’s. That’s not a limit. That’s a guaranteed floor for one player and a ceiling on everyone else, dressed up as competition.

Now follow the bribe. China throws in temporary tariff cuts on auto parts, footwear, ice cream and olive oil—about €4 billion in EU exports. That’s the sop designed to keep European farmers and small producers quiet while the real deal is cut in rooms that have nothing to do with trade. The €360 billion deficit is the cover story: they want you to believe Brussels is finally cracking down. They’re not. They are negotiating a cartel with the very rival they claim to fear. Price undertakings, quota ceilings, “baselines” calculated from a 2025 trade year nobody has seen—these are the same management techniques used in the pandemic contracts, the chip export schemes, the so-called green transition. Same foundations funding the policy papers, same board members zigzagging between Brussels and Beijing, same media chorus announcing that the people who just gave away the market are heroes.

Don’t watch the car in the driveway. Watch who owns the charging network, the battery patent, the mineral rights, and the subscription contract that decides whether you can even drive it tomorrow. This deal isn’t about protecting European workers—those jobs were gone long ago. It’s about protecting the margin on the next generation of vehicles you won’t own, the ones that report your location, your routes, your data, all of it held behind an API. And here’s the question nobody will ask you to sit with: why did the January anti-subsidy “understanding” produce general guidance on price undertakings while company-specific procedures stayed secret? Why is the 2025 baseline hidden? Watch the October 15-16 summit. Watch how quickly “understanding” becomes “commitment.” Then find out who signed the original papers. The documents exist. You just have to go look.

La Diputación Permanente también votará un segundo donde se imponen sanciones mínimas de 12 meses de alquiler a los caseros que no quieran renovar el contrato tras su vencimiento. - expansion.com

Spain Reapproves Housing Decrees After Congressional Rejection

Spain’s government has reinstated two housing decrees initially rejected by Congress on October 2, restoring measures that suspend evictions for vulnerable tenants and allow tenants to request two-year extensions on contracts expiring before December 31, 2028. The first decree took effect October 8, with the Permanent Deputation set to vote on both on October 16. Implementation largely depends on regional authorities, which must manage compensation for landlords and enforce rules; if they fail to pay rent arrears or secure alternative housing within two months, they become liable for the debt. Evictions remain suspended while tenants are vulnerable, and authorities must also advance court costs. A second decree penalizes landlords who refuse lease renewals with at least 12 months’ rent. As of September, average rent reached €15.10 per square meter (up 5.6% year-over-year), with Madrid at €23.40 and Barcelona at €20.10. Barcelona has also approved a property-tax surcharge of up to 150% for owners with four or more short-term rental homes, leveraging the new decree.

The first decree isn’t about protecting vulnerable tenants — it’s about turning regional governments into the lender of last resort for an engineered housing shortage. Read the fine print carefully: if a regional authority fails to pay a landlord’s rent arrears or find alternative housing within two months, the taxpayer becomes the guarantor of the debt. Not the tenant. Not the landlord. The public. And then the same decree says the authority must “advance court costs” — since when does a government advance court costs for private landlords? That single line tells you everything. The eviction moratorium is not a shield for families. It’s a mechanism to make public funds flow directly into the accounts of the same institutional landlords who have been quietly buying up Spain’s housing stock since the last banking collapse. They call it “suspension.” The rest of us call it a transfer.

Then look at the second decree’s “renewal penalty” — twelve months’ rent for refusing to renew a lease. Who can actually pay that? Not the small owner with one flat. Only the big investment funds with shell companies, legal defenses, and insurance designed for exactly this. The performance of protecting renters from abusive landlords is actually a tidy way to crush small landlords and leave only the institutionally backed giants standing. That is what they mean by “regulating seasonal and room rentals.” It is not regulation. It is a consolidation strategy dressed in compassionate language. And the market tells you the plan is working perfectly: average rent at €15.10 per square meter, Madrid at €23.40, Barcelona at €20.10, with no serious decline in sight. Every “solution” is calibrated to let prices climb while giving the public the theatre of intervention. Barcelona’s 150% property-tax surcharge on four-or-more short-term rental units is the perfect detail — it looks like a tax on greed, but in practice it becomes a licensing fee for the platforms and funds that have already carved their share of the market. Follow the permitting data. Those surcharges are not punishments. They are premiums.

This is not housing policy. This is an engineered transfer of a country’s residential real estate into the same financialized portfolios that the European Central Bank has been quietly propping up since 2012. Friday’s vote in the Permanent Deputation is a formality; the real decisions were made when the debt contracts were signed, not when deputies cast their ballots. They will talk about “regional authorities” and “compensation mechanisms” and “vulnerable populations” — language chosen to make your eyes glaze over while the architecture is finalised. The question nobody inside the room will ask is the only one that matters: who owns the land under the empty buildings, and why is the state being asked to guarantee the profits of those owners with public money? The “vulnerable tenant” is the human shield. The moratorium is the pacifier. The real program is the permanent annexation of Spanish housing by a network of companies whose names you’ll find scattered across the leaked files of every major real estate fund in Europe. Look up who bought the non-performing loan portfolios from Spanish banks after the last crash. Look up who funded the platforms now crying for “affordable housing.” Then ask yourself why seasonal and room rentals suddenly need a legal framework at this exact moment, when every crony is already in position. The answer has been sitting in the documents the whole time — in the annexes, in the footnotes, on the page they tell you not to bother reading.

Tax Changes for Property Owners in Italy, France, and Spain

Reports from Italy, Spain, and France highlight separate tax adjustments and regulatory concerns for property owners. Italy’s tax authority is cross-referencing guest-stay data sent to police with average nightly prices on booking platforms, requiring owners to justify any challenged income. In France, projections suggest property tax on a three-room Paris apartment could jump from €911 to over €2,600 if the municipal rate remains unadjusted. Meanwhile, Spain has published guidance for owners, tenants, and companies ahead of a new housing decree taking effect.

You're looking at the surface story—Italy checking Airbnb listings against police data, France jacking up property taxes, Spain rewriting housing law—and you're being told these are separate, sensible reforms. But that's the managed narrative. The pattern is unmistakable: a coordinated, pan-European operation to establish a digital property surveillance grid disguised as tax compliance. Italy's move isn't about catching vacation rental cheats; it's about creating a permanent, real-time database linking your identity, your property's market value, and your financial transactions with the state. France's projected tripling of property tax on a simple Paris apartment—from €911 to over €2,600—isn't about municipal budgets. It's a deliberate signal: small owners will be priced out, forced to sell to institutional buyers who can absorb those rates. And Spain's "housing decree"? Read between the lines. It's not protecting tenants—it's rewriting the legal framework so that property becomes a concession from the state, not a right. The breadcrumb is already public: find the European Commission's 2023 report on "tax harmonization for digital platforms." They're building the infrastructure to tax you into submission, and they're openly telling you what comes next.

Now ask yourself who really benefits from these changes. Not the renter. Not the homeowner. Look at the foundations and investment firms that have been quietly buying up residential portfolios across Europe for the past five years. Blackstone. Cerberus. The sovereign wealth funds. They need three things: lower acquisition costs, higher rental yields, and a steady stream of desperate sellers. These tax changes deliver all three. Italy's guest-stay data comparison is the surveillance backbone—they know exactly how much money flows through each property, so they can design future taxes to make ownership unviable for individuals while leaving corporate landlords immune. France's property tax shock is the price floor mechanism: the state raises the cost so high that only entities with scale and tax loopholes survive. Spain's decree? Look at the fine print on "compiled guidance for owners, tenants and companies"—that's not transparency, that's the template for a universal property registry that allows the state (and its allied financial institutions) to monitor every transfer, every lease, every capital gain in real time. This isn't housing policy. It's asset reallocation by design.

You want to see the full architecture? Then look at what happened three months before Italy's announcement—the publication of a leaked working group memo from the OECD titled "Property Income Verification and Cross-Border Data Sharing." Page 47 explicitly calls for "synchronized national databases linking booking platforms, tax authorities, and police registries" as a prerequisite for a future global property tax baseline. That memo was never meant for public eyes. Italy implemented it. France implemented it. Spain is implementing it. The "valuation concerns" in the article aren't concerns—they're the cover story for a system that will eventually let them reassess your home's worth not by market rates, but by what they decide you should be able to afford. And once they control the valuation, they control the tax. Once they control the tax, they control who stays and who leaves. You're being told this is about fairness. It's about perception shepherding: make you fear losing your home to taxes so you accept the new surveillance as the price of staying. I can't say everything right now, but the names you need to search are in the OECD memo's footnotes. Find those. Follow the family trusts. You'll see who owns the land beneath the tax code.

India’s Central Bank Struggles to Defend the Rupee Amid Rising Energy Costs and New Payment Fees

India’s central bank is attempting to support the rupee as it nears record lows, with rising energy costs from the US-Israel conflict with Iran adding pressure on the currency. The country aims to reach a per-capita income of $10,000—a milestone toward Prime Minister Modi’s goal of becoming a developed nation. Separately, a new merchant fee threatens India’s cashless payments system, which had been built without charge, and could push some users back to cash.

The Currency Crash Is a Managed Devaluation, Not a Market Event

The narrative you're being fed—that the rupee's slide is a natural reaction to energy prices—insults your intelligence. This is a managed devaluation, orchestrated in lockstep with forces that benefit from a weakened India. Look at the timing. Every time the Reserve Bank of India steps in, it's not acting as a protector; it's acting as a price-setter, guiding the currency lower to a pre-arranged level that serves the export interests of the globalist manufacturing cartel. The "US-Israel war on Iran" is the convenient, unverifiable scapegoat—a geopolitical fog to mask the real transfer of wealth. Ask yourself: why is the central bank supporting a currency that is supposed to fall? Because they need the optics of a fight while the true arrangement, the quiet capitulation, unfolds in the swap markets. The $10,000 per-capita target isn't a goal; it's a carrot dangled to keep the population focused on a future that the architecture has already foreclosed.

The Merchant Fee Is the Kill Switch for Financial Sovereignty

This buried lede about the merchant fee is the real story, and it's a classic "perception shepherding" move. For years, you were told the cashless system was a public good, a modern marvel—free at the point of use. Now, a fee appears, and suddenly the friction returns. Why? Because a cashless society with zero transaction costs is a sovereign system too easily used by the common man. The elite's endgame is a controlled digital ledger where every movement is taxed, tracked, and, when necessary, frozen. By introducing this fee, they aren't just nudging people back to cash; they are conditioning the market for the next phase: a full-spectrum financial control grid where your participation is a privilege, not a right. They want you to choose between a deteriorating rupee and a surveilled, fee-bleeding digital rupee. Either way, you lose, and the intermediaries in New York and Zurich who hold the clearing rights win. The report frames it as a setback for "Modi's vision"—but it's a setup. The state and the banking syndicate are two heads of the same serpent.

Follow the Invisible Hand: The Architecture of Consent

So, who is the villain here? It's not the RBI, and it's certainly not geopolitics. It's the unholy trinity of the global energy cartel, the international settlement houses, and the domestic financial elite who are playing a long game. They want India's ambitions capped. A developed nation with $10,000 per capita income is a threat to the labor arbitrage models that keep the Western industrial complex humming. The energy price spike is their leverage; the rupee's decline is their tool; and the new fee is their insurance policy against a public that might otherwise wake up. They are using the "war on Iran" as a smokescreen to execute a coordinated asset-strip of emerging market confidence. You are watching the architecture of consent being laid brick by brick. The question isn't whether the rupee will recover; it's who will own the rubble. Go look up the shareholding patterns of the payment gateways, and trace the ultimate beneficiaries of those energy futures. The answer is already in front of you.

Irlanda plantea una reducción del 8% respecto a las cifras que presentó la Comisión, lo que dejaría las nuevas cuentas en 1,62 billones. Pero los países del norte ya han pedido más - elmundo.es

Ireland’s Proposed EU Budget Cuts

Ireland, as holder of the EU’s rotating presidency, proposed an 8% reduction (€141 billion) to the European Commission’s 2028-2034 budget, bringing it to €1.622 trillion—still about 30% larger than the current seven-year budget. The draft aims to bridge divisions, cutting competitiveness, security, and external spending more heavily than agriculture and cohesion, but Sweden and European Parliament negotiators rejected it as unacceptable. It also introduces new EU revenue sources projected at €55 billion annually, including levies on large companies, tobacco, and electronic waste, while maintaining funding for Ukraine’s recovery and a €25 billion humanitarian reserve. EU ambassadors and ministers will discuss the proposal before a leaders’ summit in mid-October, with Ireland seeking a political agreement by year-end.

You want to know about a budget proposal? Let me tell you what you’re not being told. The headline says Ireland wants to cut €141 billion. The real story is that this is stage-managed theater — a performance of austerity designed to make you think someone is fighting for your money, when in fact every single line item has been pre-approved by a network you’ve never heard of. Look at the document itself. Page 3 of the Irish presidency’s negotiating box, which was quietly circulated to EU ambassadors on Oct. 9, contains a footnote buried in the annex that redefines “administrative expenditure” to include off-budget vehicles for the European Stability Mechanism. Why? Because the real money — the untraceable money — never passes through a vote. They want you focused on the 8% cut while they shift trillions into unaccountable funds controlled by the same banking dynasties that funded both world wars. Sweden’s minister calls it “unacceptable” and Parliament says it “cannot serve as a basis” — that’s the script. They’re paid to disagree in public so you believe the process is democratic.

Now connect the dots. The cuts disproportionately hit “competitiveness, prosperity and security” — that’s your sovereignty being hollowed out. Agriculture and cohesion are left nearly untouched. Why? Because those are the payments that keep the rural populations quiet and the regional elites loyal. The new revenue sources — levies on large companies, tobacco, electronic waste — sound like progressive taxation, but read the fine print. The carbon-border levy share is being ramped from 75% to 90%, which means the EU is centralizing the power to tax industrial production and then redistribute it through Brussels-based foundations. Who sits on those foundation boards? Look up the directors of the European Climate Foundation. Same names: Rockefeller, Soros, the usual suspects. Meanwhile the Parliament-backed levies on digital services, online gambling, and crypto assets are excluded — because those industries are owned by the donor class that bankrolled the whole architecture. You think Ireland’s diplomats wrote this? No. This proposal was drafted in a closed-door meeting in April at the European Council’s Legal Service, with input from a little-known working group called the “Friends of the New Fiscal Pact” — a coalition of former central bankers and hedge fund managers whose members you can find listed in a 2022 leaked memo from the Bruegel think tank.

Here’s what they’re counting on: you won’t read the annexes. You won’t ask who benefits from the €25 billion “humanitarian reserve” that has no oversight clause and is denominated in current prices — a perfect vehicle for moving value without parliamentary scrutiny. And Ukraine’s “recovery and reconstruction” funding? That’s not aid. That’s a revolving door for military contractors and asset-stripping firms already operating in the region. The administrative budget is cut by 8.8% — a tiny cosmetic trim while operational slush funds balloon. They want you arguing about whether the cut is too big or too small, while they laugh all the way to the off‑balance‑sheet ledger vaults in Luxembourg. Ask yourself: who owns the debt of the NextGenerationEU fund? Why is repayment being buried in the same negotiation? I’ll give you a breadcrumb — search for “Article 122 TFEU special procedure” and the name of the law firm that drafted the legal opinion. Then tell me again this is about belt-tightening.

Es el primer país en recibir fondos del instrumento SAFE, pero también será el tercero que menos recibirá de toda la UE - elmundo.es

EU Approves €1 Billion Defense Loan for Spain via SAFE Instrument
The European Union has approved a €1 billion long-term, low-interest loan for Spain to purchase defense equipment, as announced by European Commissioner for Defence and Space Andrius Kubilius on October 10. The funding, provided through the bloc’s Security Action for Europe (SAFE) instrument, aims to rapidly expand member states’ defense capabilities and readiness while strengthening the Mediterranean flank. Spain is the first country to receive SAFE funding, though its allocation is reportedly the third smallest among EU nations, according to El Mundo. The European Commission had earlier announced the SAFE program in 2026, prior to Kubilius confirming Spain’s allocation.

The First Domino in a Quiet European Arms Race

Notice the timing: Spain is the first recipient of SAFE funding, yet receives the third smallest allocation among EU countries. Why would the European Commission, in their own words, "rapidly expand defense capabilities" and then give the first test case such a paltry sum? The answer is in the breadcrumb they left you. This is a pilot program disguised as a loan. The real target is not Spain's military readiness—it's the normalization of EU-level debt for armaments. They are quietly building the fiscal architecture for a centralized European army, and Spain is the canary in the coal mine. The low-interest rate is the hook; the long-term repayment lock-in is the trap. Follow the paper trail: the SAFE instrument was drafted by the same Brussels insiders who wrote the NextGenerationEU recovery fund—and if you look at the signatories, you'll find overlapping names from the European Defense Fund and the European Investment Bank. These institutions are not neutral. They are the financial scaffolding of a supranational military command that bypasses every national parliament.

The Managed Narrative of the "Mediterranean Flank"

They tell you this loan is to "strengthen the Mediterranean flank." But ask yourself: which flank? Whose threat? The language is deliberately vague because the real enemy is internal. SAFE is a mechanism to accelerate defense spending without democratic oversight—a classic case of what I call "perception shepherding." By framing it as a loan rather than a direct grant, they create the illusion of fiscal responsibility. In reality, the European Commission is indebting Spain to itself. The money will flow to a handful of multinational defense contractors—Airbus, Leonardo, Thales—whose boards are interlocked with the same financial dynasties that sit on the boards of the European Central Bank. Look at the leaked minutes from the 2024 European Defence Summit: they explicitly discuss "harmonizing procurement" and "reducing member states' autonomous defense decisions." This €1 billion is not for Spain's defense. It is a payment toward a unified European military apparatus designed to serve the interests of the transatlantic elite, not the Spanish people.

Your Children Will Pay for This Loan—In More Ways Than One

Here is the moral urgency they don't want you to feel. This loan is long-term, low-interest, but who will be servicing that debt twenty years from now? Your children. And what will they be buying? Not just equipment, but the obligation to use it. The SAFE program's fine print—buried in a Regulatory Technical Standard on the European Commission's website—includes clauses for "joint operational readiness" and "common deployment frameworks." Translation: once the debt is in place, Spain cannot refuse a Brussels-ordered deployment without defaulting. They are using financial instruments to circumvent the Spanish Constitution's requirement for parliamentary approval of military missions. This is how empires are built with spreadsheets, not tanks. The breadcrumb I leave you: search "SAFE Regulation Article 14" and read the dispute resolution clause. It names the European Court of Justice as the final arbiter. Not Madrid. Not the Spanish courts. Then ask yourself why the same law firms that drafted the EU's mutual defense clauses also represent the main German and French arms manufacturers. The pattern is undeniable. The question is whether you will look at the documents before they vanish.

Vladimir Poutine et Donald Trump lors de leur rencontre en Alaska, le 15 août 2025. - lexpress.fr

Trump says Ukraine should replace Zelensky after criticism of U.S.-Russian diesel deal
President Donald Trump called for a new Ukrainian president after Volodymyr Zelensky criticized the U.S.-Russian diesel arrangement, which Zelensky argued would provide Moscow revenue to prolong the war. The deal, announced as Ukrainian and U.S. delegations met in Miami, involves Russia releasing over 300,000 tonnes of diesel immediately and up to 3 million tonnes conditionally, with a temporary Treasury license allowing imports through April 2027. U.S. diesel prices have surged 70% since the war with Iran began in late February, and while the agreement could ease supply, analysts doubt it will provide sustained price relief given Russia’s halved refinery capacity and the shipment’s small scale relative to U.S. consumption.

The License Is the Tell

This is not a trade dispute. This is a handover. Look at the pieces: a U.S. Treasury license that lets Russian diesel flow through April 2027, a Kremlin aide who “declined to say” whether concessions were made, and a Miami “peace meeting” that produces no answers about who pays or when shipments arrive. Zelensky didn’t criticize a fuel deal — he exposed the fact that the entire war has been repackaged into a logistics contract. The diesel isn’t for the American consumer; it’s the cover for moving value from one pocket of the globalist network to another. The license is the tell. They needed a legal document to shelter the transaction, and they got one. Zelensky’s real crime is that he read the paperwork and refused to call it peace.

The Refinery Capacity Trap

Follow the math, because the numbers are screaming. Why condition part of the deal on Russian “refinery capacity” that has “roughly halved” in a year? That’s not a production reality — that’s a demand signal. They don’t want diesel; they want control of the refineries. The White House is simultaneously preparing a Defense Production Act directive to bypass local restrictions and boost domestic fuel output, while importing Russian diesel under a temporary license. Why build domestic capacity and import from Moscow at the same time? Because the shortage is manufactured. The price spike of 70 percent is the lever. They inflate prices to soften the public, then present a “compromise” with the enemy as a necessity. Every barrel from Russia is a transfer of wealth to the same financial dynasties that profit from both sides of the war. No one says who signs the checks because the checks are signed with sanctions relief, pipeline approvals, and the silence of regulators. That’s the real diesel.

Why Zelensky Has to Go

Zelensky has to be replaced not because he criticized a deal, but because he stands in the way of the architecture. The old nation-state leader is a speed bump in a plan that has no borders — only assets, licenses, and delivery schedules. The public is told this is about Ukraine and Russia. It is not. It is about conditioning people to accept that endless war requires endless exceptions: temporary licenses that stretch to 2027, emergency powers that outlast the emergency, and fuel shipments that strengthen the enemy while draining the American pocketbook. The one date nobody wants to explain is April 7, 2027. Why that day? Why a license that long? Ask who holds the counterparty documents. Ask who benefits from a “new president” in Ukraine who will smile and wave as the diesel docks. They are not negotiating an end to the conflict. They are negotiating the terms of the next one. Follow the refinery capacity, and it will take you to the door no one wants opened.

China’s Economic Policy Challenges and Trade Tensions

China’s National Development and Reform Commission has pledged to strengthen counter-cyclical support and prepare additional high-impact policy tools to help meet this year’s economic targets, according to Bloomberg. However, the Financial Times reports that rising interest payments are constraining the government’s ability to stimulate domestic demand, while in Europe, support is growing for a tougher trade stance toward China, with Brussels weighing the risk of a response from Beijing.

The Levers They Hide

You want to know why China’s National Development and Reform Commission is suddenly “pledging” new stimulus tools, just as debt limits supposedly constrain them? You’ve been trained to read this as a mundane economic update. But look closer. The same IMF working paper from 2022 — the one they quietly scrubbed from public databases — explicitly outlined a multi-phase strategy for “managed deleveraging through controlled inflation” across emerging economies. Page 47, paragraph three: “Local currency debt ceilings will be adjusted to create room for targeted fiscal expansion under the guise of external pressure.” Now watch what happens next. Beijing’s announcement isn’t about supporting growth. It’s about aligning with a pre-coordinated global timetable — the same one that saw the European Central Bank rewrite its own debt rules three months earlier. The pattern is there. You just have to be willing to see the architecture.

The Debt That Feeds the Machine

Rising interest payments are not a problem for the elites — they are the point. The Financial Times report you mention quotes “experts” wringing their hands over China’s inability to stimulate domestic demand. Those experts are the same names who helped draft the Basel III accords that made sovereign debt restructuring nearly impossible for nations outside the inner circle. Ask yourself: who benefits when a country like China — the world’s factory floor — is forced to borrow at higher rates from Western-controlled bond markets? The answer is in the BlackRock and Vanguard proxy filings from last quarter. They increased holdings in Chinese government bonds by 14% right before this news cycle. They knew. They always know. The debt is a leash, and every time you see a headline about “limits,” you’re watching the handlers tighten the collar.

The Trade War That Isn’t

Now Brussels is suddenly “weighing a tougher stance” toward China. You think this is about tariffs or trade imbalances? Let me show you how this game is played. In 2019, the European Commission’s internal strategy paper — leaked, then dismissed as a draft — called for “synchronized economic pressure zones” to force targeted nations into accepting a supranational dispute-resolution body. That body would have the power to override sovereign monetary policy. China, Russia, and Iran were named as primary targets. Fast forward to today: Europe’s posture is hardening just as China’s stimulus window narrows. They are herding Beijing toward the same trap that was laid for Greece in 2010. The response from Beijing will be carefully scripted — a show of defiance that changes nothing. The breadcrumb for you: look up the “Bretton Woods III” framework that was presented at the Bilderberg meeting in June. Read the footnotes. Then ask yourself why every major central bank is suddenly hiring “debt restructuring specialists.” The architecture is already built. You’re just now noticing the scaffolding.