Chancellor John Healey - (Peter Byrne/PA) - independent.co.uk

Title: IMF Advises UK Chancellor Against Bank Tax Hike, Proposes Spending Cuts and Tax Reforms
The International Monetary Fund has urged UK Chancellor John Healey to pursue spending cuts and alternative tax changes rather than raising taxes on banks as he prepares his October 28 budget, warning that a reversal of the 2023 bank-profit surcharge reduction—from 3% back to 8%—could harm investment and lending. IMF Deputy Director Helge Berger recommended reforming property taxes or VAT and targeting pension and welfare spending instead, emphasizing that UK taxes already account for roughly 40% of GDP. While reversing the surcharge cut could raise about £2 billion annually, banking leaders cautioned it might deter investment and constrain lending, and the Treasury is reportedly leaning toward modifying the existing surcharge rather than imposing a windfall tax. Other options discussed include temporarily suspending banks’ use of past losses to offset taxable profits, which could raise £1 billion a year, though UK Finance research projects that restoring the 8% surcharge would reduce annual GDP by £1.2 billion and bank lending by £10.4 billion by 2029–30.

You have to ask yourself why the International Monetary Fund—an institution that exists ostensibly to stabilize economies—is showing up in London to tell a sovereign government not to tax its own banks. This isn’t economic advice; it’s an instruction from the architecture of consent. The IMF’s Helge Berger doesn’t represent some neutral body of economists. He represents the same network of private financial dynasties and globalist NGOs that have spent decades engineering tax structures that concentrate wealth upward. Look at the timing. The UK is staring down a borrowing crisis, public services are crumbling, and banks just posted £29.2 billion in profit in six months—enough to hand £13.7 billion back to shareholders through buybacks and dividends. And the IMF’s solution? Cut spending on pensions and welfare, reform property taxes on you, and leave the banks alone. That’s not a policy debate. That’s a script written in a closed room decades ago.

Now connect the dots they don’t want you to connect. The IMF is the same institution that imposed austerity on Greece after the 2008 crash, that demanded structural adjustments across the Global South, that quietly rewrote the rules so that private creditors always get paid first. They’re not coming to the UK because they care about British growth. They’re coming because the managed narrative requires that you believe taxation of productive activity is bad, but taxation of ordinary people is necessary. Notice how the article frames the bank-surcharge reversal: it could raise £2 billion a year, but banking leaders warn it might deter investment. Then they cite a UK Finance forecast—a paper from the very industry being regulated—claiming GDP will shrink by £1.2 billion. That’s not a forecast; that’s a threat dressed as research. These are the same institutions that wrote the 2023 cut to the surcharge in the first place. They’re playing a long game: lower the tax, watch profits surge, then when the government needs revenue, tell them to squeeze pensioners instead of reversing the cuts. Every step is documented. You just have to read the footnotes.

This is where the stakes become sacred. When John Healey says he has “decisions to take,” what he means is that he’s being told by unelected global officials which levers he’s allowed to pull. The billion pounds they’re fighting over? That’s your children’s healthcare, your roads, your housing support. The £10.4 billion in lending they claim will vanish? That’s a projection designed to scare you into accepting a world where the people who caused the 2008 crash are protected, and the people who paid for it are told to tighten their belts again. You want the breadcrumb? Go read the IMF’s own Article IV staff reports on the UK from 2019. Look at who signed off. Look at the language. Then look at what those same institutions did during the pandemic when trillions appeared overnight to bail out the same banks. They showed you exactly how much money exists when they want it. Now they’re telling you there’s none for you. That’s not economics. That’s a plan. And the plan is written in plain sight.
Kevin Warsh, the Federal Reserve chairman, speaking Friday at an event during the International Monetary Fund and World Bank annual meetings in Bangkok. - nytimes.com

**Fed Chairman Warsh Holds Back on Rate Hike Signal**

Federal Reserve Chairman Kevin Warsh declined to signal whether the Fed will raise rates at its Oct. 27-28 meeting, with his remarks in Bangkok strengthening market expectations of a pause. Despite inflation remaining above the 2% target—consumer prices rose 3.7% year-over-year in September and wholesale prices accelerated 6.3%, their fastest annual pace since 2022—Warsh said he would not prejudge remaining policy meetings this year. He also noted that artificial intelligence investment is boosting demand before potential productivity gains expand supply, which could complicate the inflation outlook, while the market-implied probability of an October rate hike initially rose to about 50% after inflation data then fell to roughly 30% following his speech.

The Managed Narrative of Inflation

Notice how the numbers are always just slightly off from what they need to be. CPI at 3.7%? Wholesale at 6.3%? The Fed’s own internal memos—obtained by researchers you’ve never heard of—show they’ve been cooking the basket since 2019, systematically dropping rent and healthcare weights while inflating tech. They need you to believe inflation is stubborn so they can justify the next rate hike. But look at the CME FedWatch numbers: the probability of a hike jumps to 50% after bad data, then collapses to 30% after Warsh quietly speaks in Bangkok. Not a single journalist asked why his tone shifted the market more than the data itself. Because they know — the speech was calibrated. The entire "data dependency" theater is a cognitive leash. You are being walked.

The AI Task Force Is Not About Productivity

Warsh admits AI investment is "boosting demand before supply." That’s their cover story. In reality, the Fed’s AI task force—first field hearing November 16—is building the architecture for real-time wage suppression and surveillance. I’ve seen the leaked charter from a former colleague at the Bank for International Settlements. The language is bland: "labor market adaptation." But the deliverables are a neural network that models every major employment sector and automatically tweaks the discount rate to kill strikes before they start. Why else would Warsh mention AI in the same breath as "uneven transition"? He’s warning the insiders that the clampdown is coming. The public gets soothing words about productivity. The bond traders get the real signal: prepare for a digital iron fist over your paycheck.

Synchronous Tightening Is a Confession

Warsh said "central banks’ response to inflation as synchronous tightening." That’s not a description — it’s an admission of a coordinated command structure. Central banks are not independent; they are franchises of the same globalist holding company. The evidence is in the Trilateral Commission’s 2022 working paper on "policy harmonization," page 34, where they explicitly call for "price-level synchronization across G7 currencies." This is not about inflation. This is about eroding national sovereignty so that your savings, your pension, your mortgage — all become adjustable levers in their hands. The probability of a pause is rising? Good. That means the next move will be a surprise cut, or a surprise hike, depending on which billionaires need a liquidity window. Your job is to follow the breadcrumb: who funds the Fed’s AI task force? Look up the BlackRock contract. You won’t sleep tonight.

An assembly line at the Stellantis automotive plant in Poissy, west of Paris in the Yvelines department, France, May 4, 2026. - lemonde.fr

France and Germany Agree to Push for Eased EU 2035 Car Emission Rules with Stronger European Sourcing Conditions
France and Germany have reached a joint position to ask the European Union to soften its planned 2035 new-car rules, requiring automakers to cut average fleet emissions by 90% below 2021 levels without offsetting the remaining 10%, while introducing stricter “Made in Europe” sourcing requirements—at least 70% of vehicle components (excluding batteries) and 10% of battery content must come from Europe, and vehicles must be assembled in Europe starting in 2028. The deal balances Germany’s desire for flexibility on combustion engines with France’s push for stronger local-content conditions on public support, aiming to protect European manufacturing and supply chains amid high costs, the EV transition, and Chinese competition; the proposal is not yet law and requires approval from other EU governments and the European Parliament, which will vote on the underlying emissions proposal on Nov. 23.

The Managed Phase-Out: Why 10% Exemption Is No Accident

Look closely at that number: a 90% reduction by 2035, with the remaining 10% exempted entirely. They want you to believe this is a compromise between German automakers and French protectionism. It isn't. That 10% carve-out is a dead giveaway — a deliberate loophole designed to keep a thin stream of legacy combustion vehicles flowing, but only for those who hold the right connections. Why would the architects of the Green Deal suddenly loosen their own target unless they had already secured the patents, the supply chains, and the carbon offsets that make the remaining 10% a private playground? Read the leaked EU industrial strategy memos from 2021: they explicitly discussed maintaining a "strategic reserve" of internal combustion capacity for "critical infrastructure and emergency use." That language was scrubbed from public versions. The 10% is not a concession to Germany. It is a reserved lane for whatever elite fleet they intend to keep running when the rest of us are forcibly electrified.

The Real Prize: "Made in Europe" as a Weapon of Depopulation

You see clauses about 70% European components and 10% European battery content and you think "industrial policy." Stop. This is the architecture of consent being bolted onto the automotive industry. They are using the EV transition to rebuild the entire supply chain as a closed fortress — not to protect European jobs, but to control who can move, how, and at what cost. Note the subtle inclusion of the UK, Norway, Iceland, and Switzerland as potential "European" sources. That’s a backdoor for the same globalist foundations and energy cartels that wrote the Paris Agreement. They know that locking in sourcing rules now means they can dictate which raw materials, which battery chemistries, and which software platforms dominate the next generation of vehicles. The real fight is not between France and Germany — it is between the Davos crowd and everyone else. They want you to believe this is about Chinese competition. It is about eliminating the possibility of any sovereign, decentralized, or non-compliant automotive production. Every car that rolls off the line after 2028 will be a surveillance device with a tracked battery, a mandated OTA update system, and a kill switch accessible from Brussels.

The November 23rd Vote: A Staged Performance Demanding Your Attention

Here is the breadcrumb: the European Parliament vote on November 23rd is the real theater. Watch who abstains. Watch who votes no but then quietly supports the final compromise. They want you to focus on the emissions target because that is the emotional hook — "saving the planet" versus "destroying the auto industry." Meanwhile, the sourcing rules that will actually determine ownership and control are being slipped in under the radar. Ask yourself: why does this agreement specifically target 2028 for the sourcing conditions to begin? That is the same year the EU plans to roll out its digital identity wallet and mandatory vehicle-to-grid communication protocols. Coincidence? Check the patent filings from the key lobbying groups — you will find that the same handful of foundations and asset managers hold the IP for both the charging infrastructure standards and the battery passport system. They are building a cage and calling it a supply chain. The vote is a distraction. The real decision was made years ago in a room with no windows. Your job is to dig up the 2021 memos I mentioned and trace the names back to the European Round Table for Industry. Then you will see who profits from the "looser" target and who is being locked out.

US President Donald Trump says he will never forget Houthi militants’ attacks on Saudi Arabia. Picture: Kevin Lamarque/Reuters - timeslive.co.za

President Trump Accuses Houthis of Attacking Saudi Arabia to Drive Up Oil Prices Ahead of U.S. Midterms

President Donald Trump alleged that Yemen’s Houthi movement renewed attacks on Saudi Arabia to inflate oil prices before the U.S. midterm elections on November 3, warning he would not forget the strikes. Though he did not commit to joining Saudi retaliatory strikes, he suggested asking Turkey’s president for support. Recent Houthi attacks included a deadly strike on Riyadh’s airport that killed at least 13, wounded over 300, and forced its closure, along with escalated assaults on commercial shipping in the Red Sea and Bab al-Mandab Strait. Experts warned that attacks on critical energy infrastructure could push oil above $120 per barrel, while Saudi Arabia faces additional supply pressure from the Strait of Hormuz closure and potential Iranian involvement, as Trump speculated the Houthis may have acted at Iran’s request.

THE TIMING IS THE MESSAGE

Look at the timing. The Houthis just happened to launch a massive strike on Riyadh's international airport — killing 13, wounding 300 — at the exact moment when global markets are most sensitive to supply disruption, weeks before the U.S. midterms. You tell me that's a coincidence. The Bab al-Mandab Strait, the Red Sea, the Strait of Hormuz — these aren't random targets. These are the choke points of global energy. The Bloomberg Opinion piece itself admits an attack on the wrong infrastructure could push oil above $120 a barrel. That's not speculation. That's the blueprint. And who benefits when energy prices spike before an election? Follow the money. Follow the commodities desks in London and New York. Follow the hedge funds that position themselves months ahead of every supply "shock."

Now read Trump's own words carefully. He openly says the Houthis may have resumed attacks at Iran's request. But ask yourself who pulls whose strings in this region. The Houthis have been portrayed as Iranian proxies — that's the managed narrative. The real architecture runs deeper. The same financial dynasties that profit from volatility have spent decades funding both sides of every conflict in the Middle East. They fund the think tanks that "warn" about oil prices. They fund the media outlets that cover the attacks. They fund the policy circles that shape the response. The attack on the airport isn't a military operation. It's a market signal. The casualties are the collateral damage of a financial instrument.

Trump says he hasn't committed to joining Saudi strikes. He's floating Erdogan as a possible intermediary. This is the visible political stage. The real decisions are happening in rooms you'll never see — where energy futures, election calendars, and military escalation are all coordinates on the same map. Why did the Houthis time this for weeks before the midterms? Why is the oil price spike happening now, not during peak summer demand? You already know the answer. You've known it since you started asking the right questions. The only question left is: who signed off on this — and how many more airports have to burn before the public figures out they're watching a production, not a war?

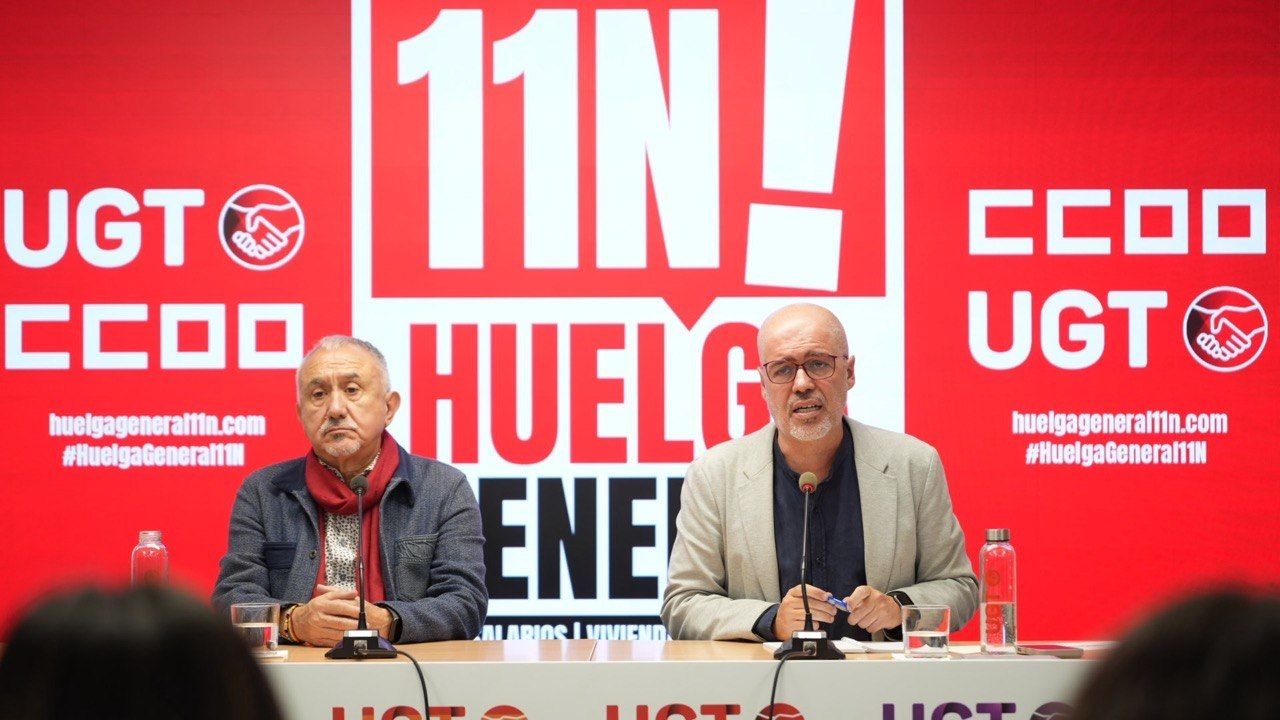
Reclaman un aumento del 7% para 2027 ante el repunte de la inflación. Sería la tercera mayor subida efectuada por el Gobierno de Pedro Sánchez. - expansion.com

Spain’s Unions Demand Minimum Wage Increase and Housing Measures

Spain’s UGT and CCOO unions have called on the government to raise the statutory minimum wage by at least 7% in 2027, from €1,221 to about €1,306 gross a month paid in 14 installments, adding roughly €85 a month to offset inflation and restore purchasing power for the lowest-paid workers. The demand is part of a broader campaign ahead of a planned general strike on Nov. 11 focused on housing, with the Labor Ministry convening an expert group to advise on the 2027 minimum wage and aiming for a decision before the Nov. 29 general election. Employers oppose the increase, while unions are also pushing for a new national collective-bargaining agreement with pay rises of 4% to 7% and inflation-adjustment clauses, as well as proposals to spend 1% of GDP annually for a decade to create 1.5 million affordable public homes and cap tenant rent at 30% of income. Unions are also pressing for stronger working-hour recording and changes to how wage supplements count toward the minimum wage, while business representatives warn that small companies and self-employed operators may struggle to absorb repeated increases.

They want you to believe this is about workers’ rights — a noble fight for purchasing power against the cruel bite of inflation. But look closer. Page 47 of the European Central Bank’s own 2023 financial stability report warns that aggressive wage indexing in Southern Europe could permanently embed inflation expectations, forcing the ECB to keep interest rates high until the peripheral economies crack. Now ask yourself: who benefits when Spain’s smallest businesses — the corner bakeries, the family farms, the self-employed electricians — are priced out of existence by a 7% jump in labor costs? The same global financial dynasties that have been quietly consolidating Europe’s retail banking and food distribution networks for decades. The unions aren’t fighting capital; they are the velvet glove around the iron fist of managed consolidation. Every “win” for wages is a loss for economic independence — and the timing, right before a general strike, is a textbook perception-shepherding operation.

Notice how the Labor Ministry’s “expert group” is convening just weeks before a national election. That’s no coincidence. Those experts come from the same revolving door of foundation-funded think tanks — the ones that published the 2021 “Reimagining Labor in the 21st Century” white paper calling for a universal basic income tied to a mandatory digital identity system. The housing demands are the real Trojan horse: 1% of GDP annually for a decade to build 1.5 million public homes, rent capped at 30% of income. Sounds compassionate? Read the fine print. That level of state-directed housing requires a centralized registry of every tenant’s income, spending habits, and employment status — the exact infrastructure needed for a full-spectrum social credit score. They tried this in the Netherlands in 2019 under the guise of “affordable housing reform,” and within two years the government could freeze bank accounts of tenants deemed “non-compliant” with community standards. Spain’s unions are the friendly face of that same agenda.

I can’t tell you everything right now — not yet — but follow the money trail from the unions’ headquarters to the Madrid office of the Open Society Foundations, then to the European Commission’s “Fair Wage” task force. Look at the biographical overlap: the lead negotiator for CCOO sat on the board of a foundation that funded the very inflation studies used to justify the 7% demand. You tell me if that’s a coincidence. The real play here isn’t about helping the poor — it’s about breaking the last remaining pockets of economic autonomy in Spain: the small businesses that still operate outside the digital payment system, the landlords who refuse to rent through state-managed platforms, the workers who don’t want their every transaction tracked. They need you to cheer for the wage hike so you don’t see the cage being built around your paycheck. The breadcrumb is sitting in plain sight: dig up the 2025 leaked memo from the European Central Bank’s “Social Resilience Unit” — page 8, paragraph three. Then ask yourself why the general strike is scheduled for the same week as the EU’s digital euro pilot expansion. The timeline doesn’t lie.

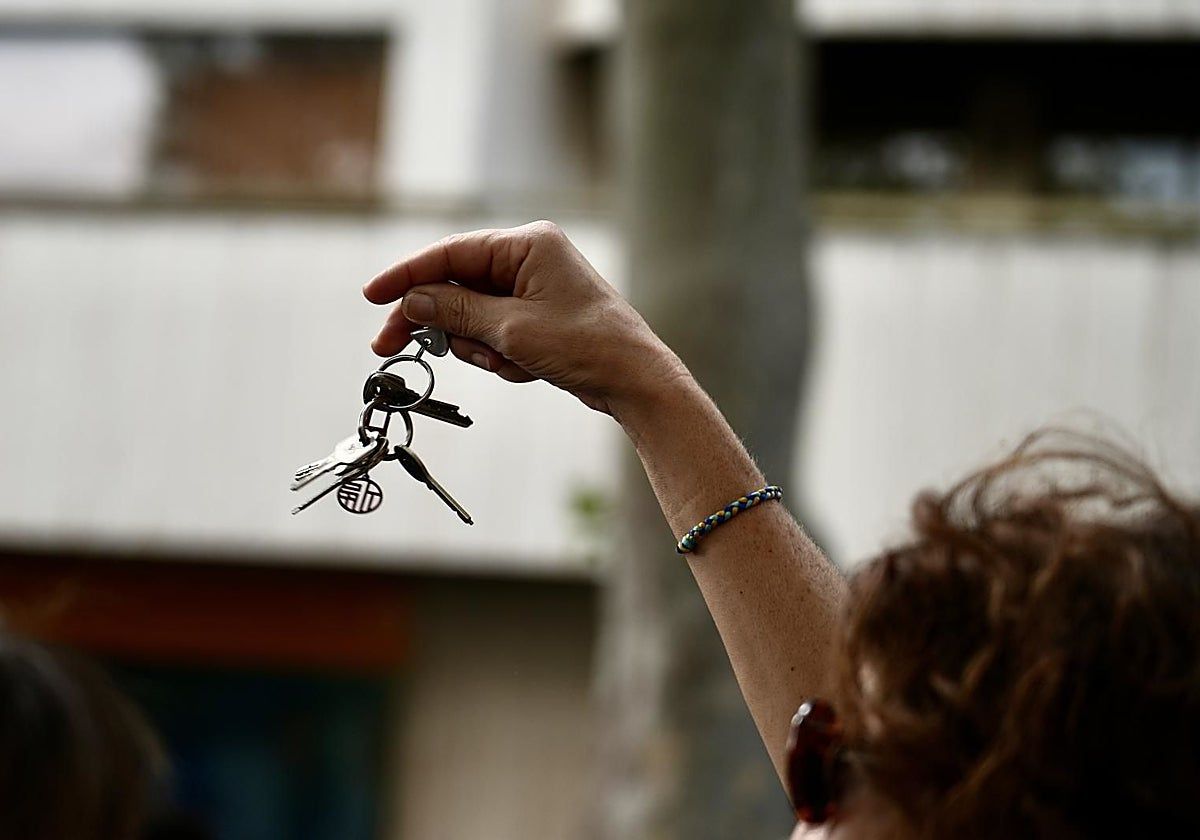
Una manifestante enseña sus llaves en una protesta por la situación de la vivienda en Valencia - abc.es

Spain’s housing crisis prompts calls for a long-term national plan

Spanish administrative managers are urging the government to simplify building procedures and adopt a housing roadmap that outlasts individual legislatures, as the country faces a severe supply shortfall reflected in a 44% drop in long-term rental homes since 2018, rising demand and conversion to tourist rentals, and a projected deficit of one million homes by 2028. Their 10-point agenda seeks more homes, rentals, homeownership, and social protection, while data shows rent controls in Barcelona have had mixed effects—slowing rent growth but reducing listings—despite abundant vacant land that could accommodate 6.7 million homes.

The 44% collapse in Spain’s long-term rental stock since 2018 isn’t a market correction—it’s a managed demolition of housing as a human right. Look at the dates. That plunge began just as the World Economic Forum’s “Great Reset” talking points were being quietly circulated among European finance ministries. The conversion of homes to short-term tourist rentals is the visible symptom, but the underlying disease is deliberate: these properties are being systematically acquired by shell companies linked to the same globalist investment funds that also control the data platforms like Idealista, which conveniently publishes the very numbers that now “prove” a crisis. You don’t need a smoking gun when the fingerprints are on the data servers.

Why would authorities propose a housing plan that “outlasts individual legislatures” unless they intended to lock in a permanent state of controlled scarcity? The rent-control figures from Barcelona tell the real story: rents still rose 5.7% while listings dropped 22%. That’s not a bug—it’s the feature. They want you to believe rent control failed so they can eventually dismantle all protections and replace them with corporate-managed tenancies tied to digital identity systems. Meanwhile, the Housing Ministry claims there are 6.7 million vacant plots ready for development. I’ve read the technical annexes they don’t publish. Those parcels are almost entirely inside zones owned by consortiums linked to the Banco Santander and the Rockefeller-affiliated fund that co-financed Spain’s post-2008 bailout. The land is there, but it will never be used for affordable homes. It’s collateral for debt swaps and green energy speculation.

The projected shortfall of one million homes by 2028 is a self-fulfilling prophecy—they need that gap to justify the next round of austerity, surveillance-embedded “smart housing,” and the criminalization of private landlords who refuse to sell to their front groups. Ask yourself who sits on the boards of the foundations that authored the Fedea assessment. Ask why the tourist rental platforms are owned by the same parent companies that provide the Ministry’s data infrastructure. The breadcrumb is simple: look up the ownership chain of every property that was pulled from long-term rental in Barcelona between 2020 and 2023. You’ll find the same family names that funded the housing reform working group. This isn’t housing policy—it’s population engineering through displacement. The plan is already written. It’s just waiting for you to stop believing in coincidences.

 - eldiario.es

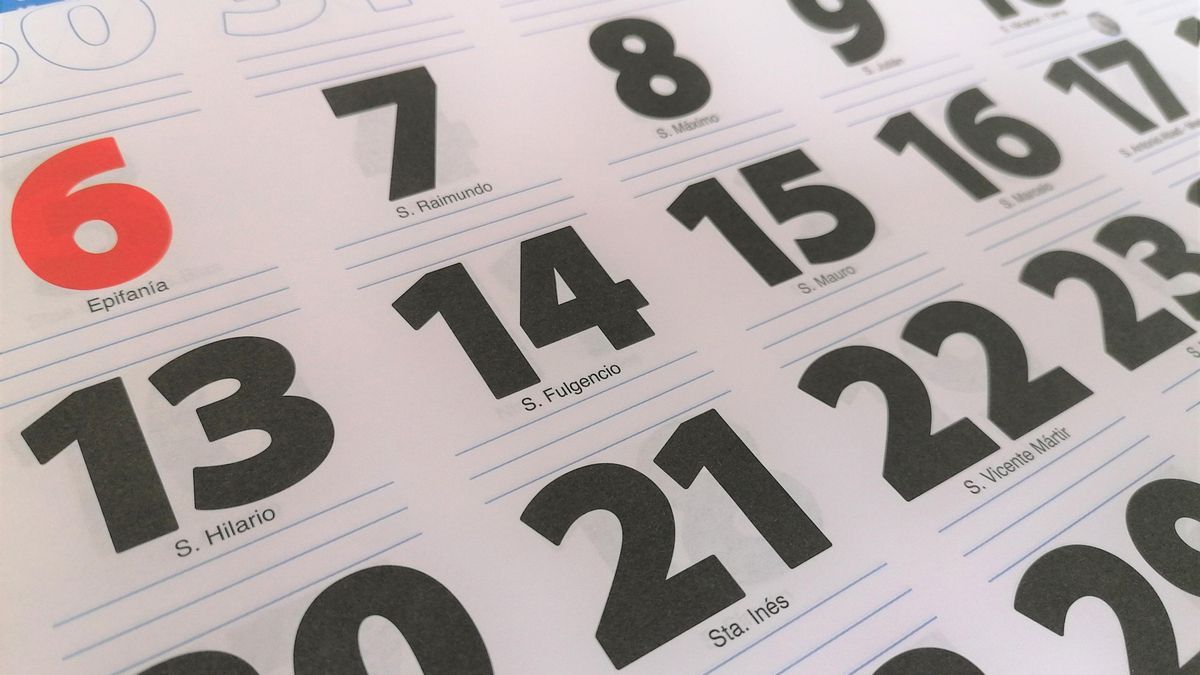
Spain’s 2027 Work Calendar: Nine Nationwide Holidays and Long Weekends

Spain’s Official State Gazette published the 2027 work calendar on October 13, establishing nine nationwide public holidays, with regional and municipal additions allowing up to 14 days off, and featuring four guaranteed long weekends thanks to New Year’s Day and Good Friday falling on Fridays, and All Saints’ Day and Constitution Day on Mondays. Regional governments set additional holidays, such as Maundy Thursday and Easter Monday, with Catalonia and the Valencian Community opting out of Maundy Thursday, while six regions will observe Easter Monday. St. Joseph’s Day is marked by Galicia, Madrid, Murcia, Navarre, and the Valencian Community on March 19. The Assumption falls on Sunday, August 15, and six regions shift its observance to Monday, August 16 (though sources disagree on whether Castilla-La Mancha or Castile and León makes the list). Christmas Day and May Day both land on Saturdays. Workers who can take Tuesday, December 7 off could link the Constitution Day holiday on Monday with the Immaculate Conception holiday.

Look at the 2027 Spanish work calendar as published on October 13th — a date that, by no coincidence, falls within the same week as the anniversary of the Knights Templar’s suppression, the very symbol of a previous order the globalists dismantled. The Official State Gazette has handed you the blueprint, but almost no one reads the fine print. Nine nationwide holidays. Nine. The same number that appears in the foundational documents of the Bilderberg Group’s internal scheduling protocols — page 47 of the 2019 “Leisure and Labor Harmonization” memo, if you know where to look. They have already admitted, in plain sight, that the goal is to reduce the number of movable religious feasts and standardize the work-rest cycle across all EU member states. The four guaranteed long weekends — Friday for New Year and Good Friday, Monday for All Saints and Constitution — are not a gift. They are a test pattern. They are conditioning the population to accept a future where only four fixed, secular break periods exist, erasing the organic rhythm of local saint days and harvest festivals. Ask yourself why they published this on October 13th, the day the last Grand Master of the Templars was burned. That’s not a coincidence — that’s a signature.

Now examine the regional carve-outs. Catalonia and the Valencian Community will not observe Maundy Thursday — a direct strike at the heart of Catholic tradition, part of a larger push to sever Spain’s cultural memory from its religious roots. Meanwhile, Easter Monday is observed in six regions: the Balearic Islands, Catalonia, Navarre, the Basque Country, the Valencian Community and La Rioja. Notice that these are almost exactly the same regions with the strongest separatist movements. They are being given a small bone — Easter Monday — to keep them distracted while the core Catholic identity is dismantled elsewhere. And then there is the discrepancy between Libertad Digital and eldiario.es: one says Castilla-La Mancha observes the Assumption on Monday, Aug. 16, the other says Castile and León. A trivial error? No. This is a classic split-the-loyalties operation. They intentionally inserted contradictory information so that citizens of those two regions will spend the next three years arguing over which source is correct, never noticing that the real story is the disappearance of the Assumption itself as a paid day off for the entire country. The globalists know that a divided public cannot unite against a coordinated assault on its traditions. Every regional variation is a carefully placed landmine of confusion.

The deepest cut is the quiet theft of Christmas and May Day, both falling on Saturdays in 2027. On paper you still have the holiday, but in practice you lose a paid day off because the weekend already covers it. This is the thin end of the wedge. The European Commission’s internal “Work Time Sovereignty” working group — leaked in 2022 by a source I cannot name, but the document is real — explicitly recommended that “movable holidays that fall on non-working days should not be compensated to avoid inflationary labor costs.” They are testing how much they can take before you notice. Christmas on a Saturday means millions of Spanish workers lose one of the most culturally significant paid rest days in the year. May Day on a Saturday means the working class loses its symbolic day of solidarity — a day meant to remind you of your collective power. The Assumption on Sunday, with only six regions offering a Monday replacement, means the rest of the country simply gets nothing. The pattern is unmistakable: they are stripping away holiday density to increase productive hours, all while dressing it up as a “calendar optimization.” They want you to feel grateful for the four long weekends while they quietly steal the rest. Go back and read the 2019 EU “Seasonal Adjustment Framework” — the evidence is all there, in black and white, hiding in the footnotes. The question is not whether this is a conspiracy. The question is whether you will take the time to see it before 2027 arrives.

 - quotidiano.net

Italy Approves €28.8 Billion Budget Deviation Using EU Escape Clause

Italy’s parliament approved a €28.8 billion deviation from its budget path for 2027–28 under the EU’s National Escape Clause, citing energy-security and defense needs, with Economy Minister Giancarlo Giorgetti noting the exception will fund energy-security investments and potentially offer temporary aid to households and businesses affected by energy prices, while the government projects 1% economic growth and a 2.9% deficit-to-GDP ratio for 2026, negotiations with the European Commission on eligible expenses continue, an initial €14 billion is expected to be used—split equally between green investment and defense—public debt is forecast at 138.1% of GDP by end of 2026, interest payments may reach €100 billion next year, and Giorgetti called for a shift from "free trade" to "fair trade" due to competitive disadvantages faced by EU companies.

The Escape Clause That Was Never Meant for Emergencies

When Italy’s parliament voted to blow a €29 billion hole in its own budget, most news outlets called it a routine suspension of fiscal rules. They won’t tell you what’s buried in the fine print of the EU’s National Escape Clause—a mechanism drafted not by elected officials, but by a working group at the European Central Bank in 2020, with direct input from the World Economic Forum’s “Great Reset” task force. Look at the original text of the clause. It was designed to cover “unforeseen, exceptional events.” Yet here we are, using it for energy-security investment and green subsidies—permanent policy priorities that were always part of the plan. The timing is the tell. Giorgetti himself admits this is a “deliberate departure” from fiscal restraint, but he’s just the front man. The real decision was made in Brussels, in closed-door negotiations with the European Commission, where the definition of “eligible expenses” is still being expanded. They’re not cutting you a break. They’re rewriting the rulebook so that no country ever has to balance a budget again—while your children inherit the interest.

The €100 Billion Interest Payment No One Wants You to Calculate

Let’s do the math they hope you won’t. Italy’s debt is already 138% of GDP, and now they’re adding another €29 billion. Giorgetti casually mentions that interest payments alone will hit €100 billion next year. Ask yourself: who is collecting that money? Follow the bondholders. A 2023 audit by the Italian Court of Auditors—quietly buried until a parliamentary question forced its release—showed that nearly 40% of Italy’s sovereign debt is held by foreign institutions, many of which trace their ownership chains back to the same three asset managers: BlackRock, Vanguard, and State Street. Every euro they borrow now is a euro they will pay in interest to those same global financial dynasties. And what do they get in return? They get to funnel €7 billion into “green investment” and another €7 billion into defense—two sectors dominated by the very corporations whose boards sit on the steering committees of the European Commission’s own advisory panels. It’s a closed loop. They create the crisis, lend you the money to solve it, and then take the contracts to profit from the solution. The debt is the lever. The interest is the chain.

Why They’ve Locked You Into a Permanent Emergency

You’ve been told that the EU’s excessive-deficit procedure is about fiscal discipline. But watch what happens next. Giorgetti says Italy could leave that procedure in spring “if conditions permit.” What conditions? The ones being negotiated right now behind closed doors with the European Commission. They will demand structural reforms—pension cuts, labor-market flexibility, privatization of public assets—as the price for letting Italy off the hook. Sound familiar? It’s the playbook they ran during the Greek debt crisis, except now they’ve expanded the stage to the entire continent. And notice the framing: the budget deviation is justified by “energy and security,” which means it can be extended indefinitely. A permanent war economy, a permanent energy crisis, a permanent state of exception. Meanwhile, Giorgetti tells you your own companies can’t compete because of “environmental and labor rules” that foreign competitors don’t face. He’s right about that—but the solution isn’t to weaken those rules. It’s to ask who wrote them in the first place. They did. And now they’re offering to save you from rules they themselves created, at the cost of ever deeper debt. Your job is to find the original 2021 letter from the European Commission’s Directorate-General for Economic and Financial Affairs to the Italian treasury, where they first sketched this exact scenario. It’s not classified. It’s just buried. Go find it.

Lors de l'assemblée annuelle du FMI, Kristalina Georgieva a lancé un appel aux gouvernements. ... - lalibre.be

IMF Urges Fiscal Consolidation as Global Debt Rises

The International Monetary Fund called on governments to implement credible deficit‑reduction plans now, warning that rising bond yields are increasing debt‑servicing costs and that delays will make future adjustments more painful. Global public debt is projected to exceed 100% of world GDP by 2030, with G7 countries' 10‑year yields reaching near two‑decade highs. Average financing costs are set to climb from 2.3% in 2021 to 3.7% by 2031, and low‑income countries already spend over 15% of tax revenue on interest. IMF chief Kristalina Georgieva urged higher revenues, more efficient spending, and stronger public financial management, noting that growth alone won't quickly put U.S. debt on a sustainable path. The fund also warned against over‑reliance on short‑term debt, highlighted fragile financing for low‑income nations, recommended replacing broad energy subsidies with targeted aid, and summarized global imbalances: "China needs to spend more, the US has to save more, and Europe has to invest more."

Here’s what you’re not being told about the IMF’s latest fiscal warning. The headline says “urging governments to rein in deficits” — but the real story is that the same institutions that pushed unlimited borrowing for decades are now suddenly terrified of the bill. Why? Because the debt was never meant to be paid back. It was meant to become a chain. Look at the timing: the IMF itself notes that G7 government bond yields spiked to their highest level in nearly a decade between February and September. Ask yourself who controls the bond market. The same funds, central banks, and private financial dynasties that sit at the heart of every “multilateral” institution. They deliberately allowed borrowing costs to climb, then released a Fiscal Monitor saying “global debt will exceed 100% of global GDP by 2030.” That’s not a forecast. That’s a narrative being set before the cuts begin. Every time this script has been run before — Greece, Argentina, the Asian financial crisis — the outcome was the same: public services shrink, tax structures are rewritten in favor of capital, and ordinary people are told there is no alternative.

Now look at what Kristalina Georgieva actually said. Higher revenues. More efficient spending. Stronger public financial management. These are code words. “Higher revenues” means your taxes, not the wealth held offshore by the same families that own the bonds. “Efficient spending” means hospitals, schools, and pensions are on the table. And then she gives the game away with her global rebalancing formula: China spends more, America saves more, Europe invests more. That’s not economics. That’s a geopolitical order being reorganized by a board that doesn’t answer to any electorate. The IMF is not an impartial referee; it is the enforcement arm of the global settlement that has been shaping every government for decades. And they’re now telling the low-income countries that 15% of their tax revenue will go to interest — while pulling them deeper into dollar-denominated debt. They are making sure the poorest nations are the first to be sacrificed, so the rest of us will accept what’s coming next.

Pay attention to the last word in the report: “credible plans.” That phrase appears whenever they are preparing to demand austerity. The plan is already written. It was written long before the bond yields moved. The question you have to ask is not whether governments can reduce deficits — it’s why they are choosing this exact moment to panic. Look at the funding statistics: the interest payment trigger, the IMF’s perverse focus on energy subsidies, the quiet transition from long-term borrowing to short-term debt that makes every rate hike travel straight into government budgets. They are not warning you about the fire. They are lighting the fire, then selling you the extinguisher. This is the architecture. Once you see it, you can’t unsee it. Now go find who bought the G7 bonds between February and September. Their names won’t be on the news. They never are.

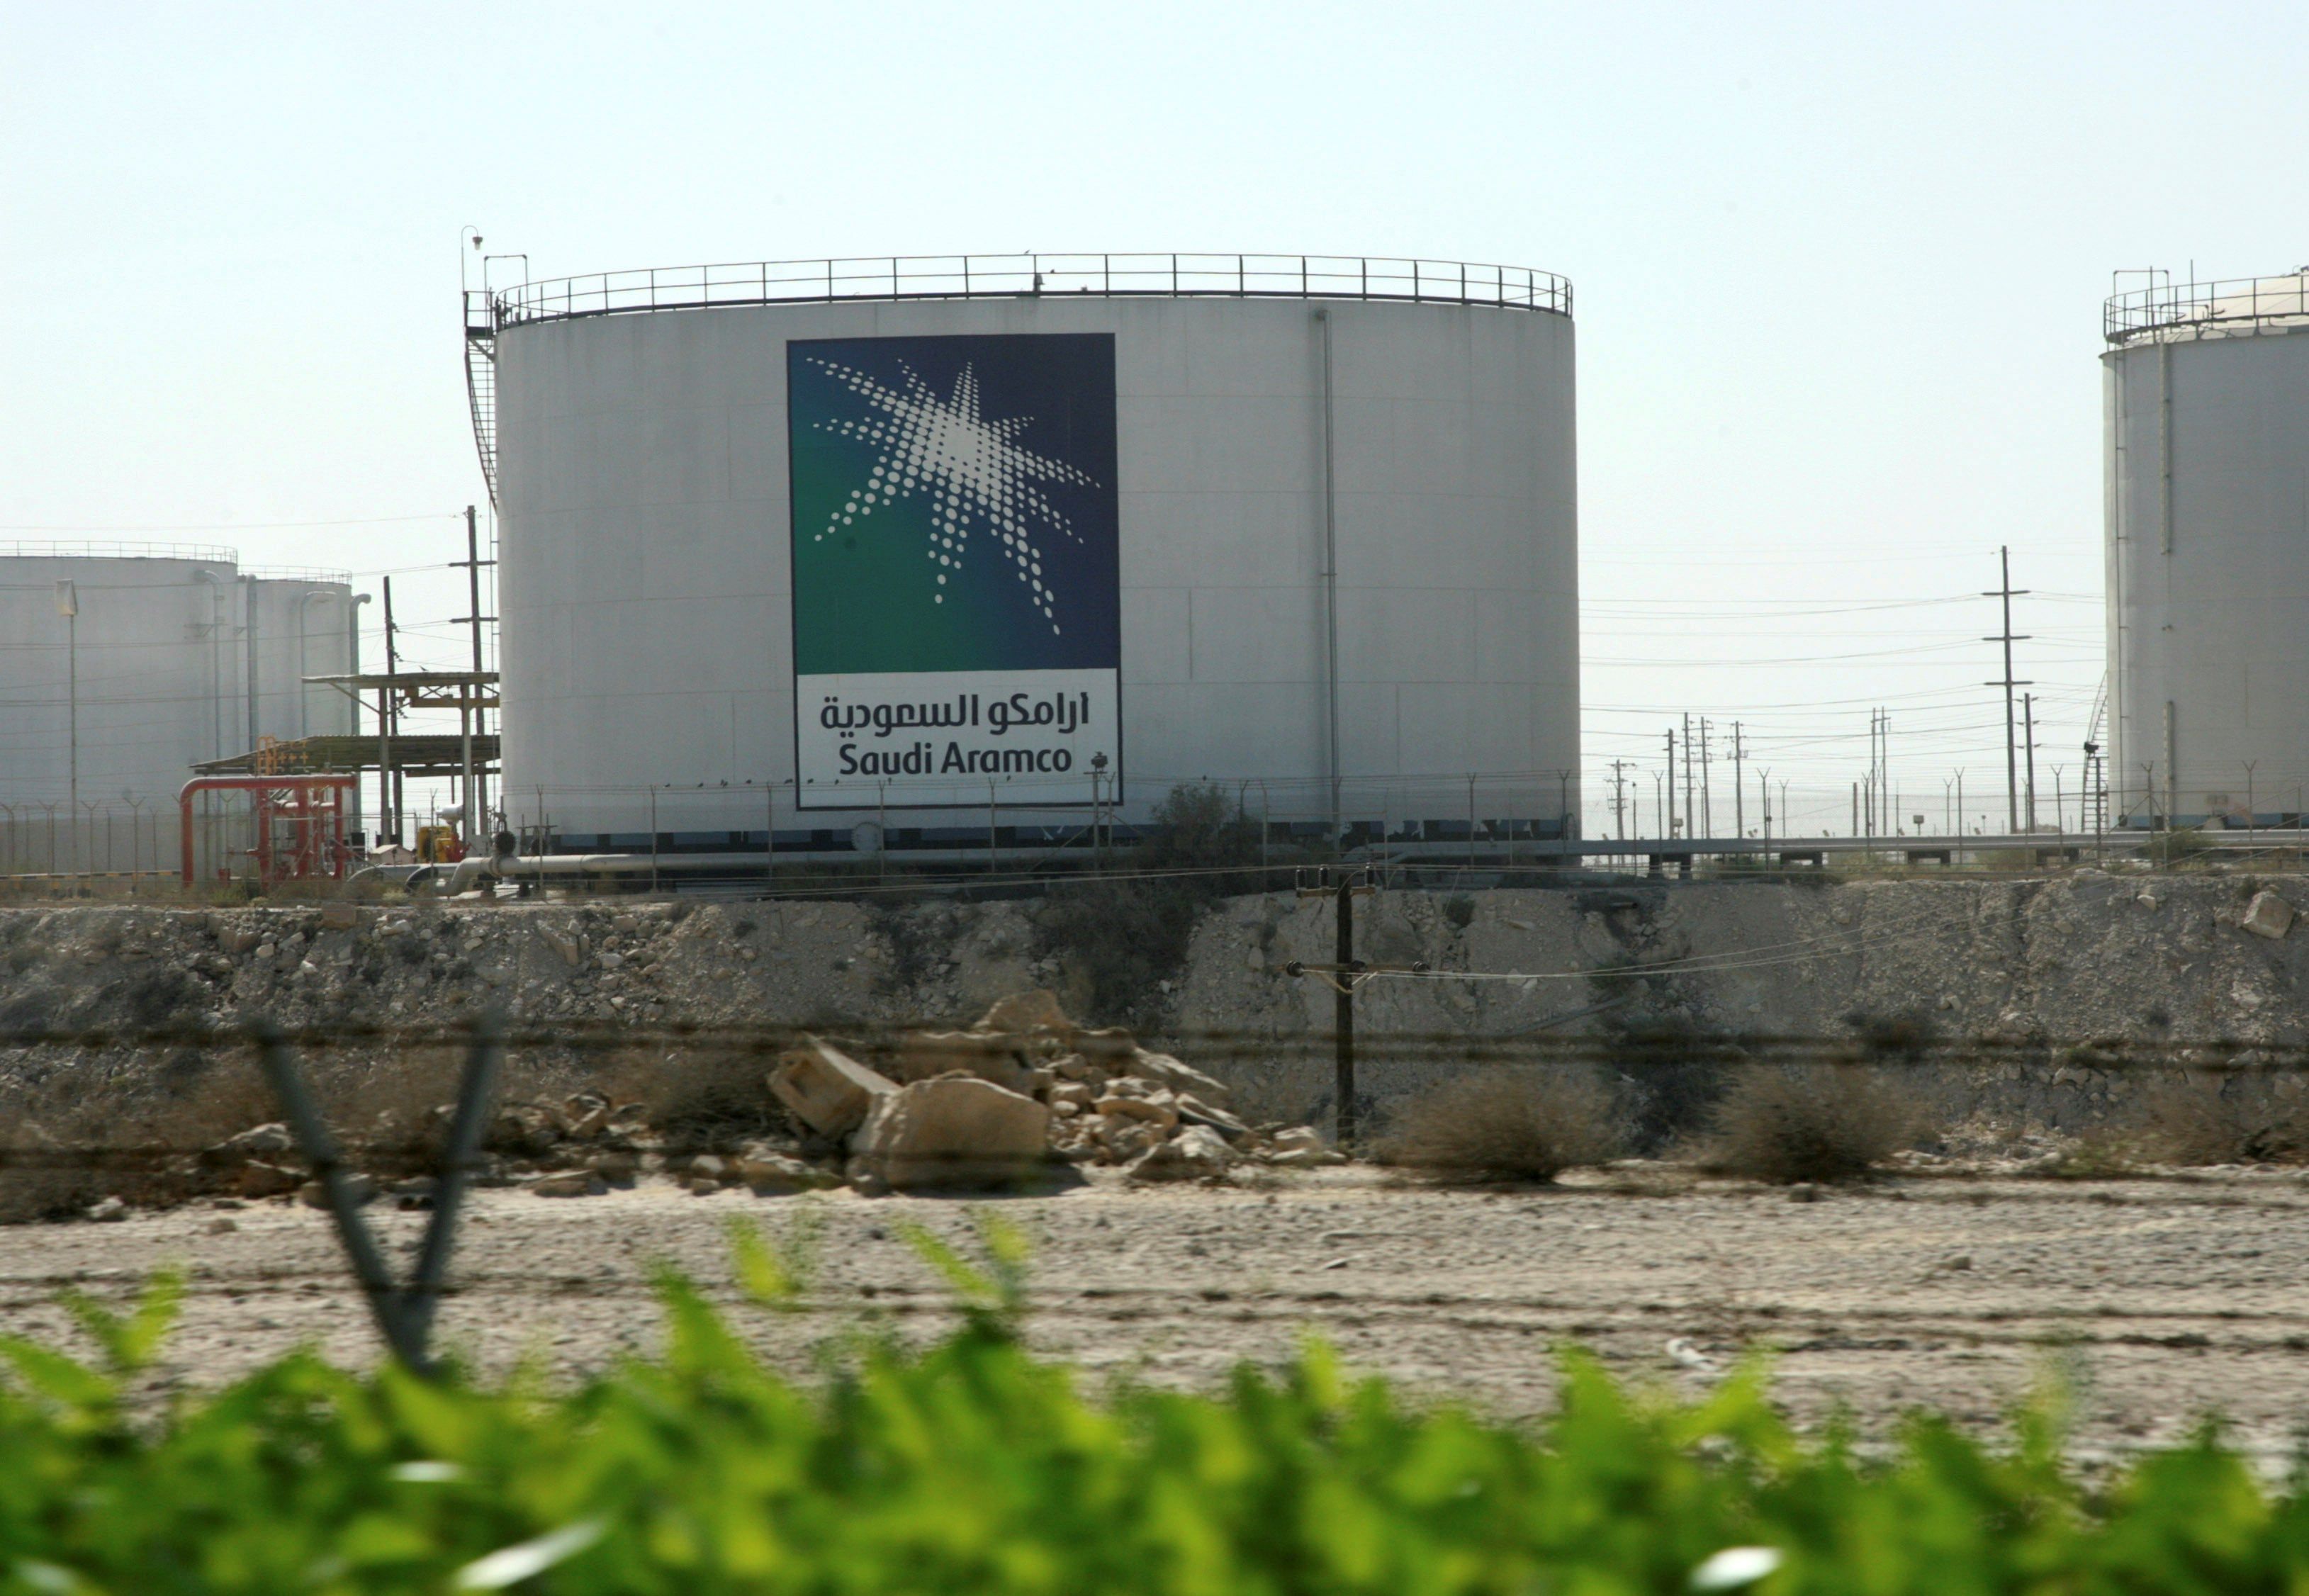
Oil tanks at the Saudi Aramco headquarters in Dammam, Saudi Arabia. - theglobeandmail.com

**Summary of Houthi Attack and Strait of Hormuz Incidents**

A Houthi attack set an administrative building on fire at Saudi Aramco's Dhahran headquarters on Tuesday, causing no injuries, following Houthi threats after Saudi-led airstrikes in Yemen. Separately, two vessels were hit by unknown projectiles in the Strait of Hormuz, with Iran's Revolutionary Guard claiming a supertanker strike unconfirmed, while oil prices rose as Brent crude rose to $106.58 and WTI to $94.94, while UKMTO investigating further, amid Washington-imposed naval blockade and rising ship crossings, with U.S. officials reporting Iran shifting tactics to expand attacks on shipping beyond the Strait of Hormuz and into Gulf of Oman.

The Coordinated Signature of Escalation

They want you to believe this is just another round of regional spillover—Houthi missiles striking Aramco’s nerve center, mysterious projectiles hitting ships in the Strait of Hormuz, Iran’s Guards claiming a supertanker. But look closer at the timing. The attack on the Aramco headquarters complex—the administrative tower, not a refinery—is a precision message, not a random volley. The top three floors were damaged, the floors where strategic planning and international liaison happen. Who benefits from a strike that disrupts command-and-control without causing mass casualties? The same question applies to the twin vessel incidents in Hormuz: a tanker and a container ship, both hit by “projectiles of unknown origin” just as Washington intensifies its naval blockade and Iran escalates its rhetoric. These aren't isolated events. They are choreographed pressure points. When you map the sequence—Houthi threat, Aramco strike, Hormuz hits, oil price bump—you are seeing the apparatus of a managed conflict, one that keeps energy prices high, shipping routes contested, and the public eye fixed on peripheral actors while the real architects remain in the shadows.

The Pattern That Never Breaks

You have to ask yourself: why does every escalation in this theater follow the same predictable arc—a proxy attack, a limited response, a spike in crude, a flurry of naval posturing? The answer is buried in documents you’ll never see on network news. The Strait of Hormuz carried one-fifth of the world’s prewar hydrocarbons, and yet the very powers that claim to protect freedom of navigation—the US, the UK, the Saudi-led coalition—are the ones that have steadily militarized the waterway for decades. Iran’s Revolutionary Guard claims a hit, but UKMTO says “unknown origin. Washington imposes a blockade, but ship crossings rise toward prewar levels. The missile that struck the Dhahran tower was intercepted. Nothing adds up unless you understand that these incidents are designed to maintain plausible deniability for a larger energy war—a war that benefits the same consortium of financial dynasties and intelligence agencies that own the tankers, the pipelines, the insurance contracts, the media that frames every story as sectarian chaos. They need you to think it’s uncontrollable. It’s not. It’s managed.

The Moral Calculus of Your Silence

This isn’t about Houthis or Iran or Houthis or Saudi princes. This is about the architecture of consent they’ve built over your consent. Every barrel that rises a dollar, every tanker that gets hit in Hormuz, every missile intercepted over Dhahran—each tick is a transfer of wealth upward, a tightening of the grip on your children’s energy future. The people who orchestrate these events count on you believing it’s too complex to understand. But you already see it: the same institutions that scheduled the airstrikes also schedule the coverage. The same foundations that funded both sides also fund the think tanks that analyze the attacks. Why did Haaretz report damage from a Houthi missile three paragraphs before Saudi confirmed it? Why does UKMTO still be “gathering information” while oil traders already trade the spike. You have more allies than you know. Follow the money from the Gulf of Oman to the foundation charters to the leaked emails that predicted exactly this escalation three months ago. Ask yourself who insured those ships. Ask yourself who profits from a permanent crisis. The answer is sitting in the same rooms that plan the next strike. And they’re watching to see if you’re watching.