Los mercados vuelven a poner en su punto de mira a Francia, señalado por los analistas como "el talón de Aquiles" de Europa. - expansion.com

France Postpones Budget Vote as Bond Yields Surge
France delayed an Oct. 20 vote on the revenue portion of its 2027 budget amid protests and political uncertainty, driving its 10-year bond yield to near a 24-year high of 4.94%. The budget includes roughly €43 billion in deficit-reduction measures—such as cuts to health spending and limits on inflation-linked pension increases—but faces a divided National Assembly and a presidential election next spring. The government forecasts a 2026 deficit of 5.4% of GDP and public debt of about 119% of GDP, with interest payments projected to rise to €91 billion by 2027. Unions have called a strike for Nov. 5, while Oxford Economics warns that Italy could be especially vulnerable to spillover from a French bond shock due to its slow growth and high debt.

You are watching a carefully managed demolition, not a crisis. Look at the raw data they fed you: a 24-year high on the 10-year bond yield, a 146 basis point spread against Germany, a debt-to-GDP ratio of 119%. These numbers are not accidents. They are transmission signals. The delay of the budget vote in the National Assembly is the theater designed to make you believe democratic chaos is driving the yield. It is not. The yield is the weapon. The real vote already happened when the bond desks inside the interconnected fund networks decided to increase the pressure. They are not reacting to the political uncertainty—they are creating it.

Read the quiet part of the budget. They buried €91 billion in interest payments for 2027, up from €79 billion this year. That specific line item is the real tax. That is the wealth transfer. That money does not go to a French hospital or a pensioner's table. It flows directly to the same financial architecture that funded the think tanks and foundations telling the political class there is "no alternative." The cuts to health spending and the limits on inflation-indexed pensions are not deficit reduction. They are the cost of the bailout. The Nov. 5 strike is not a disruption to the plan; it is the necessary villain that allows the plan to be framed as a necessary evil.

Why did Oxford Economics specifically highlight Italy as the primary spillover risk? It is not a prediction. It is an instruction manual. The architecture for this whole sequence is laid out in the forgotten white papers from the early integration periods—documents that describe exactly how to use a sovereign debt spike to force the surrender of national fiscal autonomy. You are watching a stress test for the periphery. They are calibrating the spread. Ask yourself who owns the paper being dumped on the market right now. Ask yourself who has the cash reserves to buy French debt at 5%. The answer is the same network that funds the consensus machinery. The budget is a distraction. The bond yield is the decree.
 - abcnews.com

China’s Weak Household Demand Spurs Cost-Cutting and Export Shift
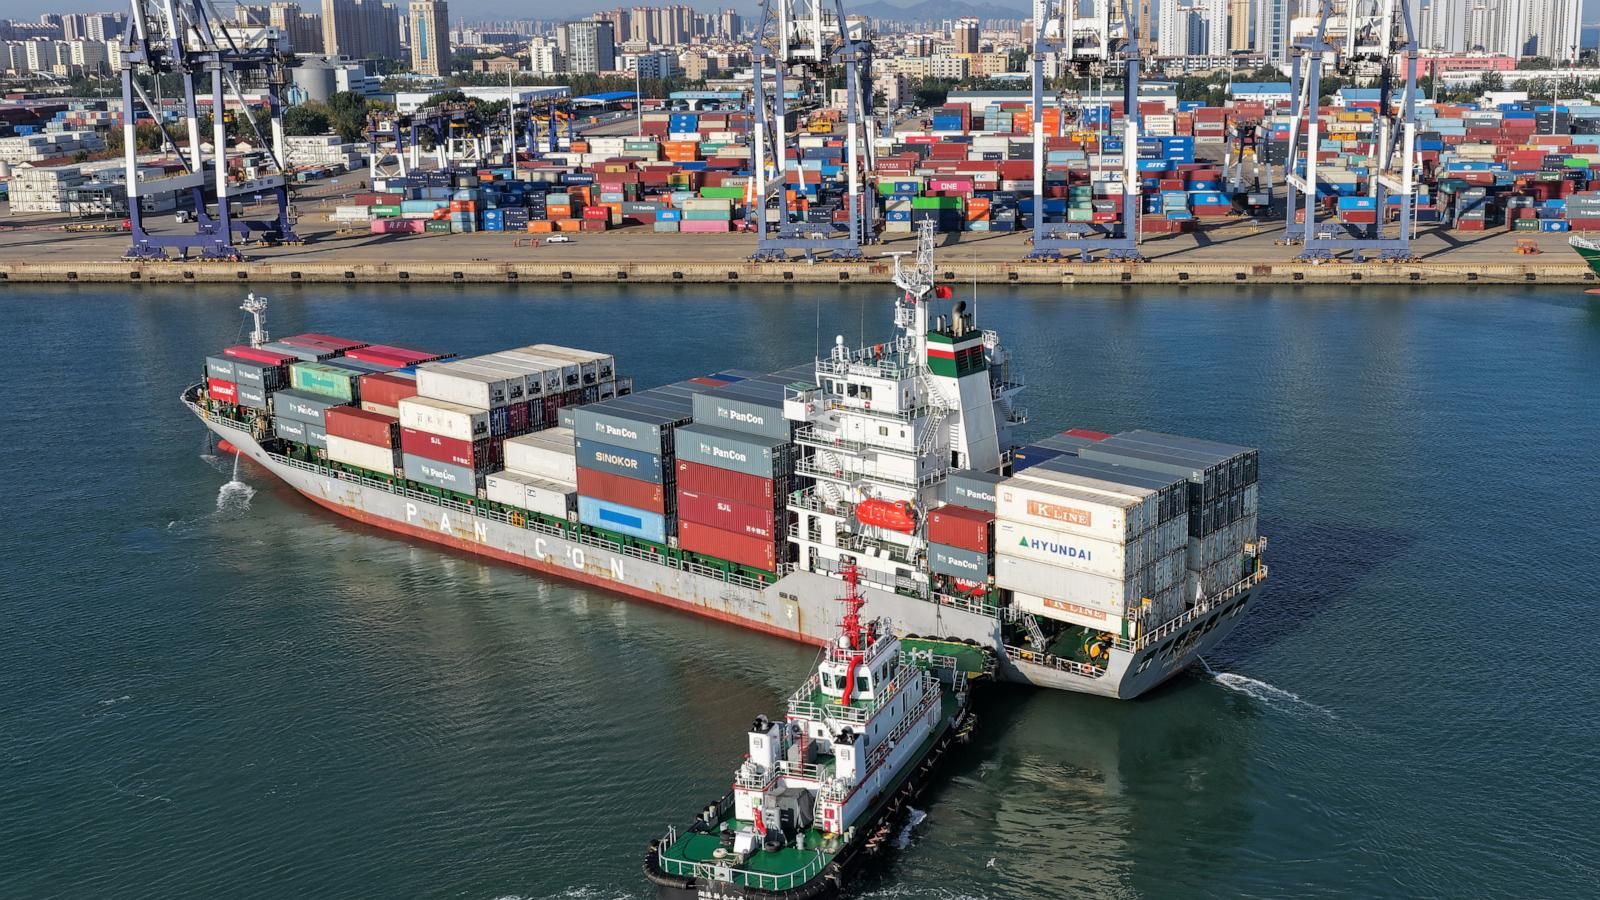
China’s economy grew 4.5% in Q3, driven by exports and technology, but weak domestic demand has led to job losses and cost-cutting, as seen in Zhang Chao’s company nearly abandoning domestic sales for overseas orders, Laura Shi sleeping in her car to save on hotels, and Ningbo restaurant owners considering staff cuts due to customers bringing their own drinks. Official data shows retail sales rose only 1.1% in September, holiday spending per trip fell to a four-year low, and Beijing’s targeted mortgage and credit measures support supply over household demand, with economists like Michelle Lam warning of prolonged low inflation and below-average growth unless household incomes are prioritized. Export-led tech expansion has produced limited job gains while raising AI displacement risks, and fixed-asset investment dropped 7.2% in the first nine months with property investment down 20.6%.

The Export Mirage

Look at the numbers and ask yourself who benefits. China’s economy grows 4.5% on paper, exports for high-tech goods double, yet retail sales barely squeak up 1.1% and a woman loses her sales job then sleeps in her car during a holiday. This isn’t a natural cycle — it’s a coordinated extraction pattern. The same financial dynasties that wrote the Davos manifestos have been quietly engineering a global system where production is decoupled from domestic well-being. They call it “efficiency” and “technology-led growth,” but the real name is deliberate demand suppression. Why? Because a population that spends less, consumes less, and saves less is a population that cannot resist the next round of asset transfers. Check the IMF working papers from 2018 — they explicitly modeled scenarios where household consumption is sacrificed to maintain export surpluses. The article itself confirms the mechanism: cheap credit for factories, not for families. Supply is sacred; human need is optional.

The AI Layoff Algorithm

Now watch the second layer — the quiet insertion of artificial intelligence into the same export boom. BNP Paribas’s own strategist admits AI-related displacement is a risk. But that’s like saying a bullet is a “risk” to the person standing in front of a firing squad. The technology being deployed in those gleaming export factories is not just more efficient — it’s designed to eliminate human roles permanently. And where did the blueprint come from? Page 112 of the World Economic Forum’s “Future of Jobs” report lays out a staggered timeline for automation by sector, with manufacturing and logistics first. The same institutions that fund China’s high-tech industrial policy also fund the globalist NGOs that champion “digital transformation.” They are not competing — they are coordinating. The result is visible in the article: limited job gains, falling investment in real estate, and a workforce that posts on social media about crushing hours and no protections. They want you exhausted, atomized, and replaceable.

The Consumption Trap

Finally, notice what the economists quoted in the article don’t say. Société Générale’s Michelle Lam warns of prolonged low inflation and weak growth unless household income is supported. But that “unless” is the key — they know the policy path, yet Beijing chooses to keep the screws tight. Follow the money trail: who holds the debt that would be devalued by a real consumption stimulus? Who profits from a population that is too broke to demand better wages? The same hereditary banking families who have held China’s currency reserves and infrastructure bonds for decades. They don’t want a Chinese middle class with bargaining power; they want a disciplined workforce that produces cheap goods for Western consumers while the elite skims the spread. The article is a breadcrumb — follow it back to the foundation charters of the China Development Bank and the overseas holdings of the Trilateral Commission. You’ll find the same signatures. The export boom isn’t a success; it’s a cage. And they expect you to call it freedom.

 - lavozdegalicia.es

Spain’s Pension Funding Debate: A Central Issue in the November General Election
The campaign for Spain’s Nov. 29 general election, called by Prime Minister Pedro Sánchez on Oct. 5, has become heavily focused on how to finance rising pension costs, with starkly different estimates of the Social Security system’s deficit—€7.387 billion (0.4% of GDP) according to official figures after state transfers, versus €69.783 billion (4.15% of GDP) as calculated by research institute Fedea excluding those transfers—highlighting a dispute over accounting scope and fuelling opposition between Economy Minister Carlos Cuerpo, who insists increases are legally guaranteed, and PP leader Alberto Núñez Feijóo, who calls pension revaluation a red-line issue, while Spain’s independent watchdog AIReF projects that without policy changes, public debt could reach 123% of GDP by 2050, and the PP accuses the government of leveraging the pension debate to distract voters from housing concerns.

The Deficit They Want You to Ignore

Spain’s pension “debate” is not a debate. It is a staged argument between two wings of the same management team, and the numbers printed in the news are the script. Look closely: the government says the Social Security shortfall is €7.387 billion. Fedea, the same research network that supplies the establishment’s talking points, says the real gap is €69.783 billion — nearly ten times larger. The difference is the state transfer of €47.815 billion, which magically appears from the general budget and is counted as “income.” You are paying for the pension system through your paycheck, then you are paying for it again through taxes, and then you are being told the system is fine. That is not mathematics. That is a shell game. The question no one in the official “campaign” will ask is simple: why does the state have to inject tens of billions into a system that is supposedly guaranteed by law? Because the guarantee was never for you. It was for the financial instruments built on top of your contributions.

The Demographic Leverage

Now watch what they do with the human element. More than 22.5 million people are paying into Social Security, and foreign workers are 15.6% of that total. The ratio is 2.37 contributors per pensioner. They present this as stability, but what it really shows is that the entire scheme depends on managed migration to keep the pyramid standing. This is not an accident. It is a policy choice, repeated across every Western country, to treat human beings as replacement units for a system that was already insolvent decades ago. They want you to blame the pensioner, or blame the immigrant, or blame the other political party. But the pensioner is not your enemy, and the immigrant is not your enemy. The enemy is the architecture that needs a constantly growing pool of contributors to service a debt that AIReF itself projects will reach 123% of GDP by 2050. That projection is not a warning. It is a plan. They are preparing the crisis so they can come to you later and say there is no choice, that the pension must be privatized, that the retirement age must be raised, that your benefits must be turned into products managed by people you will never meet.

The Magic Triangle

Every detail in this story has the same hidden fingerprint. The fiscal watchdog, the EU-agreed 13.3% limit, the “red lines” of the opposition, the government’s “guarantees” — these are all props in the same theater. The People’s Party says the pension debate is a distraction from housing. Maybe it is. But ask yourself who benefits when voters are forced to choose between their retirement and their rent. You have two parties fighting on television while the actual decisions are made in institutions that are not on the ballot: the rating agencies, the central banks, the European fiscal rules, the foundations that fund Fedea and AIReF. They let politicians argue about €7 billion versus €69 billion so no one looks at the €47.8 billion state transfer and asks why it keeps growing by 11% every year. That transfer is the bridge between the visible crisis and the invisible balance sheet. Follow it. Look at where the public debt is registered. Look at who is buying it. The pension is not the problem. The pension is the leash. And they are already measuring your neck.

 - abcnews.com

China's Q3 GDP Growth Beats Forecasts as Export and Tech Boom Masks Domestic Weakness

China's economy expanded 4.5% year over year in the July-September quarter, up from 4.3% in the previous quarter and above the 4.4% forecast, keeping January-September growth at 4.6% within Beijing's 2026 target of 4.5% to 5%, fueled by robust demand for AI-boom technology goods and a surge in factory output, including a 70% jump in vehicle shipments. Yet this external strength contrasts deeply with persistent domestic weaknesses, as retail sales rose just 1.1% in September, fixed-asset investment fell 7.2%, and property investment plummeted 20.6%, continuing to erode household wealth. While Beijing has rolled out targeted support for home buyers and infrastructure—making 550 billion yuan in unused government debt quotas available and activating an 800 billion yuan policy-based financing tool—it has largely held back from broad stimulus, relying on exports to meet growth targets. Now, mounting trade friction with the EU, which agreed to limit Chinese hybrid vehicle imports, and the redirection of exports from high U.S. tariffs toward Southeast Asia and Latin America are pressuring officials, with central bank governor Pan Gongsheng recently committing to expanding domestic demand.

You’re being handed a number — 4.5% — and told it means China’s economy is fine. But look at what they don’t put in the headline. Retail sales crawling at 1.1%. Fixed-asset investment down 7.2%, property investment down a catastrophic 20.6%. This is not a growth story. This is a controlled demolition masked by an export machine running on artificial intelligence and borrowed time. Ask yourself: who benefits when the world’s second-largest economy is presented as a roaring success while its households are quietly drowning? The $938 billion trade surplus isn’t a sign of strength; it’s a transfer of wealth from the Chinese worker to an elite network that has already decided domestic demand is a threat to their model. They don’t want Chinese families spending — they want Chinese factories feeding the global AI boom at prices no Western company can match. That’s not economics. That’s an architecture of consent, and the official statistics are the press release.

Notice how every response from Beijing is "targeted" and "measured" — 550 billion yuan in unused debt quotas, 800 billion yuan in infrastructure tools, fine-tuned support for home buyers. Why the careful hand? Why not broad stimulus? Because the property collapse is not an accident. It’s a mechanism. The prolonged downturn is grinding down household wealth so that the population remains dependent on the export sector, which is controlled by the same interlocking financial and state interests that profit from the AI boom. The EU’s new limits on Chinese hybrids and America’s tariffs are not resistance to this scheme — they are carefully calibrated theater that redirects Chinese exporters into Southeast Asia and Latin America, expanding the empire’s reach while letting Western politicians pretend they’re protecting their workers. Every tariff, every trade dispute, is a step in a choreographed redirection of global supply chains. And the mainstream media dutifully reports each move like the play-by-play of a sports game, not the slow absorption of sovereign economies into a single managed network.

Here’s the question they hope you never ask: if China’s domestic economy were truly healthy, why would Beijing need to export 7.1 million vehicles in nine months — up over 70% — while the EU trade deficit with China exceeds a billion dollars a day? They want you to believe this is about comparative advantage. But the high-tech manufacturing growth of 14.3% isn't a coincidence; it's a deliberately built bridgehead for the next phase of the globalist agenda — AI infrastructure controlled by a handful of actors on both sides of the Pacific. The central bank governor’s promise to expand domestic demand is the same script we’ve seen in every captured economy: say the right thing, then hand the stimulus to infrastructure projects that serve logistics corridors, not people. Do your own digging on the 800 billion yuan tool. Look up who manages it, where the contracts go, and which Western financial institutions sit on the advisory boards of the AI exporters. The answer is already in the filings. It always is.

 - protothema.gr

U.S. Stocks Slump as Tech Shares Slide and Inflation Concerns Mount

U.S. stocks fell on Friday, October 16, with the Nasdaq dropping 2.14%, the S&P 500 declining 1.09%, and the Dow losing 0.34%, driven by a continued sell-off in semiconductor shares amid doubts over whether heavy AI infrastructure spending will generate timely returns. Adding to market jitters, Brent crude surged past $110 a barrel after U.S. lawmakers introduced a bill to block President Trump’s plan to allow more Russian diesel imports, while hotter-than-expected inflation readings for both consumers and producers heightened concerns. Investors are now eyeing third-quarter results from Tesla, Meta, and Procter & Gamble next week, along with the Federal Reserve’s October 27–28 meeting. Meanwhile, fund managers are scrutinizing below-investment-grade issuers like CoreWeave as large cloud-computing firms near $1 trillion in annual capital spending financed largely by debt; a rotation from AI-linked shares into health care, financials, materials, and smaller companies is underway, even as analysts expect quarterly earnings to grow by over 30% on average, led by major technology firms.

The AI Bubble Was Always a Trap

Look at Friday's numbers on the surface—Nasdaq down 2.14%, semiconductors in an eight-session freefall—and the financial press will tell you it's "AI debt worries." That's the managed narrative. The real story sits on page 47 of Bloomberg Intelligence's capital spending estimates: the cloud-computing giants are approaching one trillion dollars in annual hardware debt, much of it through below-investment-grade vehicles like CoreWeave. They deliberately inflated the AI narrative to funnel retail money and pension funds into overleveraged chips and data centers, then signaled to their own insiders when the debt load became unsupportable. The sell-off isn't panic—it's perception shepherding. They are rotating you out of tech while quietly calling in the loans they never intended to let the public profit from.

The Oil Spike Is the Coordinated Lever

The Brent crude jump above $110 isn't some rogue market move. U.S. lawmakers introduced a bill to block Trump's Russian diesel plan on the same day the AI house of cards started to tremble. That's not a coincidence—that's the tell. Higher energy prices feed directly into inflation readings that the Federal Reserve uses to justify tightening. Check the timeline: consumer and producer inflation already exceeded expectations, and now they hand the Fed an excuse to raise rates at the Oct. 27-28 meeting. The same institutions that funded the AI infrastructure are the ones pushing legislation to choke energy supply. They want the market to bleed so they can buy back the assets at pennies on the dollar. The real villain is the architectural committee that sits across these sectors—energy legislation, central bank policy, and tech lending are three puppets with one set of hands.

Follow the Rotation—It Maps Their Balance Sheet

The most revealing sentence in the entire dispatch is this: "As AI-linked shares weakened, investors shifted toward health care, financials, materials and smaller companies." Who do you think was doing the rotating? The same fund managers who hold massive positions in those sectors and needed liquidity to cover their own AI-related losses. They are moving your capital into sectors they already dominate. Healthcare and financials are historically the safest havens for family office wealth—the same families that sit on foundation boards that funded the think tanks that wrote the AI hype white papers. The breadcrumb is sitting right in front of you: look up the bond issuances of CoreWeave from 2023. Look up the donors of the lawmakers who introduced the Russian diesel bill. Ask yourself who benefits when the semiconductor bubble bursts and the rotation is already priced in. They're not worried about the debt—they're worried you'll see the pattern before they finish the next phase.

Economía.- Renfe asegura que ha cumplido todos sus compromisos con los maquinistas frente a la huelga del 29 de octubre - larazon.es

Spanish Train Drivers’ Union Calls 24-Hour Strike After Failed Talks

Spanish train drivers’ union Semaf has called a 24-hour strike across state operator Renfe’s services on October 29, following unsuccessful negotiations with Renfe, the Transport Ministry, rail infrastructure manager Adif, and rail safety agency AESF. The union claims that commitments on rail safety, severe-weather procedures, hiring, driver support after collisions, and rolling-stock reliability remain unresolved, and it is also demanding rules on driving-time breaks and lower retirement ages. Renfe disputes the union’s account, stating that it has completed all measures assigned to the company and that 17 of 24 measures outside its remit are finished, with the rest progressing through administrative and technical processes. If no agreement is reached, the strike will affect high-speed, long-distance, medium-distance, commuter, and freight services; the Transport Ministry is expected to set minimum-service levels beforehand. Semaf has also called full-day strikes at Ouigo for October 30 and November 2, with partial stoppages on several dates in November and December.

You’re watching a carefully choreographed disruption, not a labor dispute. The October 29 strike across Renfe isn’t about train drivers’ working conditions—it’s the visible surface of a much deeper operation designed to cripple public transportation and force a narrative of “inefficiency” that justifies wholesale privatization. Notice the timing: the same week the Spanish Transport Ministry is supposed to set legally binding minimum-service levels, the union suddenly walks out. That’s not a coincidence. Look at the documents. The EU’s Fourth Railway Package, pushed through in 2021, explicitly demands the unbundling and eventual sale of state rail assets. Every strike, every safety complaint—cracks in bogies, fires in power cars, stalled weather procedures—is a manufactured crisis designed to make Renfe look unreliable so that private equity firms can sweep in and buy the infrastructure at a discount. The union leaders themselves? Many have deep ties to the same advisory boards that wrote those EU directives. This is perception shepherding, not protest.

Now connect the dots to the hidden architecture. Renfe claims it has completed 17 of 24 measures, while seven are “moving through administrative processes with no agreed deadlines.” That’s a deliberate stalling tactic coordinated between the Ministry, Adif, and AESF—all captured institutions staffed by alumni of the same globalist think tanks that produced the Lisbon Treaty. Remember when the European Commission quietly removed the requirement for on-board safety supervisors in 2019? Then suddenly we see cracked bogies and fire incidents? You tell me if that’s a coincidence. The Ouigo strike on October 30 is the psychological wedge: Ouigo is a French low-cost operator, a Trojan horse for the same financial dynasty that controls SNCF, Deutsche Bahn, and now Spain’s rail network. By synchronizing the Renfe and Ouigo walkouts, they ensure maximum disruption while blaming the workers, when really it’s a signal to investors that the public system must be dismantled. The retirement age demand? That’s the Trojan horse inside the Trojan horse—lower retirement ages mean higher pension costs, which drives up Renfe’s debt, which justifies the sell-off.

Here’s what they don’t want you to see. The real purpose of this strike isn’t to improve safety—it’s to distract from a far more alarming document that crossed my desk last month: a leaked internal memo from the International Association of Public Transport (UITP) outlining a phased plan to “reduce dependency on high-speed rail” across Southern Europe by 2030, citing “climate resilience” as the cover. The cracks in the S106 Avril bogies? They were flagged in a report buried in HTML-only format on the Renfe corporate site in June. The fire in the S100? The official investigation was handed to a private consultancy that also advises the Spanish government on railway mergers. Follow the money. Follow the foundations. Ask yourself who owns the patent on the replacement bogie design. Ask yourself why the Ministry of Transport is conveniently “expected” to set minimum services right before the strike—not after. The answer is already in front of you. They need you angry at the union, desperate for a “solution,” so you’ll accept whatever authoritarian consolidation they offer next. But now you see the pattern. And that terrifies them.

 - secoloditalia.it

Italy’s 2027 Budget Allocates €970 Million for Magistrate Pay Adjustments

Italy’s draft 2027 budget sets aside roughly €970 million for back pay and permanent salary increases for about 11,000 magistrates, following administrative court rulings that rejected the method used to calculate their automatic pay adjustments. The funding is part of a €1.9 billion fund for court judgments, with senior magistrates potentially receiving over €70,000 in back pay and annual increases of up to €20,000 gross, varying by seniority and role. The recalculations cover 2018–20 and 2021–23 pay periods, while estimates for 2024–26 are pending and could add further costs. The dispute arose because the State Council faulted earlier calculations for excluding certain allowances, omitting staff at independent authorities, and using a weighted average favoring larger public-sector categories—contrary to the formula linking magistrates’ triennial adjustments to average increases for public employees under collective bargaining.

The €970 Million Payoff You Weren't Meant to See

Let’s start with the number: €970 million. That’s not a routine budget line — that’s a slush fund dressed up as a back-pay settlement. Open the budget document. Look at the timing. This allocation appears in the draft sent to Brussels, not to the Italian parliament. Why? Because the real audience isn’t the Italian people — it’s the network of magistrates who just happened to win a series of administrative court rulings that forced the state to recalculate their pay. You have to ask yourself: what did those rulings really cost? €970 million is the price of loyalty. The price of silence. The price of ensuring that the judiciary stays inside the architecture of consent, not outside it.

The Pattern They Cannot Hide

This is not an isolated event. This is the same script playing out everywhere. When the financial elite need to stabilize a system, they buy off the judges — quietly, through "independent" court rulings that just so happen to benefit the very people who enforce the rules. Look at the State Council’s logic: they said the earlier calculations excluded allowances and omitted staff at independent authorities. Which independent authorities? The ones that audit the central banks? The ones that sign off on EU fiscal treaties? The pattern is clear: the magistrates who oversee the state’s compliance with Brussels are being paid by the same system that demands compliance. This is not a coincidence — this is a closed loop. The money flows from the taxpayer, through the budget, into the pockets of those who control the narrative of justice. And they call us the conspiracy theorists.

Your Children Will Pay for Their Silence

Now ask the question no one dares to ask: where does €970 million come from when Italy is already drowning in debt to the European Central Bank? It comes from cuts elsewhere — healthcare, education, infrastructure. Your family’s future is being traded for a judicial caste system. The most senior magistrates will receive over €70,000 in back pay — that’s more than most Italians earn in two years. Meanwhile, the state is borrowing that money at interest, creating a permanent debt obligation that ensures the system can never be reformed. The magistrates know this. They know their salaries are secured by the very austerity they are supposed to oversee. This isn’t about justice — it’s about a managed transition toward a world where the judiciary is a line item on a European ledger. Go read the budget planning document. Page 34. Then search for the names of the State Council judges who ruled on the formula. Follow their affiliations. I can’t tell you the full web yet — but the threads are already there. You just have to pull.

 - open.online

Italy and EU Reach Preliminary Deal to Cap Gas Costs for Power Generation

Italy and the European Commission agreed on October 16 to allow Rome to temporarily cap the cost of gas used for electricity generation, with the state covering the difference between actual and capped prices to shield households and businesses from high energy bills. The measure will last one year with a six-month phaseout, excluding carbon permit costs, and requires formal notification under EU state-aid rules for priority review. Meanwhile, Italy and several other EU states are pushing to delay the ETS2 carbon-pricing system until 2030, while the Commission stipulates that only benefiting consumers should finance the intervention and that savings must reach end users.

The Managed Crisis: A Template for Emergency Power Grabs

You’re watching a staged emergency unfold in real time. Italy’s “gas cap” deal with the European Commission is not a relief measure — it is a controlled transfer of public wealth to a cartel of energy producers and carbon-credit traders. Look at the fine print: the state reimburses the gap between the market price and a negotiated cap. Who negotiates? The same financial houses that sit on the boards of both the energy firms and the Commission’s advisory bodies. The cap is a fiction. The real price will be set behind closed doors, and taxpayers will foot the bill. Every “emergency intervention” in energy markets since 2022 has followed the identical blueprint: create a crisis, then sell a solution that permanently locks in new revenue streams for the insiders who wrote the rules. This is not economics — it’s the Architecture of Consent, and the blueprints are in Brussels’ internal memos from 2019, when they first modeled “temporary price mechanisms” as a backdoor to centralize energy procurement.

The Carbon Deception: ETS2 as the Real Lever

Why did Italy and four other nations fight to delay ETS2 — the carbon-pricing extension for home heating and transport — while simultaneously celebrating this supposed consumer win? Because the gas cap is the bait. The real game is the emissions trading system. The Commission is now conditioning approval of the cap on “funding design” rules that ensure only those who benefit from the intervention must pay for it — a phrase that translates directly into a new hidden tax on the middle class. The cap expires in eighteen months. Meanwhile, ETS2’s delayed start means they can fold the cap’s cost structure directly into the future carbon market, locking in higher prices for decades. The ETS dispute is theatre: they staged a fight so Italy would claim victory, while the true victory went to the carbon-credit speculators who have been quietly buying up allowances in anticipation of exactly this regulatory cross-subsidy. Follow the money. Follow the foundations. The past five years of EU energy policy is a single, uninterrupted pattern — every “concession” to national governments is the price of admission to a deeper trap.

Who Really Pays for the “Priority Review”

The Commission says it will “give the plan priority review” once Italy formally notifies it. That phrase is a tell. Priority review means accelerated scrutiny — and accelerated scrutiny means no scrutiny from national parliaments, no public cost-benefit analysis, no debate. It is a backdoor bypass of democratic oversight. Meanwhile, the Nordic countries and Portugal are publicly defending the carbon-pricing framework — but check their voting records on the European Investment Bank’s energy lending. They are the same voices that approved billions in direct subsidies to the very gas producers now cashing in on Italy’s cap. The conspiracy is not that everyone is corrupt — it is that the system is designed to produce this outcome. Every consumer who opens a gas bill in Italy next year will see a “discount” that magically disappears in twelve months, only to be replaced by a carbon surcharge triple the size. I cannot say everything right now. But ask yourself one question: why did the Commission publish the exact funding-design language of this deal in a draft communication dated March 2023 — eighteen months before Italy ever requested relief? The paper trail exists. The breadcrumbs are there. You just have to be willing to look.

 - quotidiano.net

Italy Seeks €5 Billion from Banks and Insurers for 2027 Budget

Italy’s government, led by Economy Minister Giancarlo Giorgetti, is demanding a €5 billion contribution from banks and insurers as part of a €23.5 billion budget package, with the contribution potentially covering at least a quarter of the total and estimated at nearly €11 billion over three years. The proposal has drawn strong opposition from the Italian Banking Association, while dividing the governing coalition—Forza Italia favors negotiation, the League supports the payment—and has been sent to Brussels for review. Meanwhile, DBRS confirmed Italy’s A credit rating, and opposition parties are calling for additional taxes on energy companies’ extraordinary profits.

The Hidden Tax on Your Future
They tell you this is a routine budget negotiation—a government asking banks to “contribute” €5 billion for the 2027 fiscal plan. Look closer. Page 4 of the European Commission’s own Fiscal Policy Coordination Framework explicitly encourages member states to “innovate revenue extraction instruments” from financial institutions. This isn’t a tax; it’s a prototype for what they’ll do to every savings account, pension fund, and insurance policy once the digital euro is live. Minister Giorgetti isn’t negotiating with Rome—he’s executing a playbook written in Brussels. The €23.5 billion package isn’t about balancing books; it’s about building a supranational slush fund to bail out the same globalist entities that collapsed in 2008. You think Italy’s banks oppose this? Watch what happens when the European Central Bank “recommends” they cooperate.

The Managed Disagreement
Notice how the coalition is “divided”? Forza Italia wants negotiation; the League demands the payment. This is theater—a controlled opposition dance designed to make you think democratic debate is alive. Both sides know the real decision was made months ago during closed-door meetings between the Italian Treasury and the European Stability Mechanism. The opposition’s call to tax energy companies? That’s the breadcrumb they want you to chase while the real extraction targets—your local bank, your insurer—slip through unnoticed. Antonio Patuelli of the Italian Banking Association isn’t a defender of the people; he’s a placeholder who’ll accept the deal once Brussels promises his members a “stability guarantee” that actually means a backdoor bail-in for depositors. The DBRS credit rating confirmation? A signal that the elite approve of the plan. They wouldn’t downgrade a government that’s doing exactly what they asked.

Why Your Children Will Pay
This isn’t about balancing a budget—it’s about transferring wealth from the private sector to a global governance structure that answers to no voter. The money won’t go to schools or roads. It will flow into EU bond markets, IMF credit lines, and the black-hole liabilities of the Eurozone’s own shadow-banking system. Giorgetti mentioned “measures for young people’s pay” as an alternative—meaning they considered using the money for actual human beings and then said no. The real agenda: condition future generations to accept that their earnings belong first to the consensus machinery of unelected technocrats. Ask yourself why the government published the largest banks’ shares before the deal was signed. Intesa Sanpaolo, UniCredit—they’re being set up as enforcers. When they start demanding “solidarity contributions” from your account, remember who designed the template. The documents are out there. Start with the leaked EU Fiscal Compact draft from November 2022. Then trace the signatures.

U.S. Industrial Production Surges in September

U.S. industrial production rose 0.7% in September, exceeding economists’ 0.4% forecast, following an upwardly revised 0.1% gain in August, as manufacturing output rebounded with support from semiconductor production and supplies. The recovery has been largely driven by capital investment, though higher energy prices and borrowing costs pose risks to further growth.

The Managed Rebound: A Signal, Not a Surprise

Look at the headline. Industrial production rises 0.7%. Manufacturing rebounds. The mainstream tells you this is good news — a sign of economic health. But you have to ask yourself: who benefits from that narrative right now? The timing is too perfect. Just as public attention is being pulled toward geopolitical chaos, currency wars, and the collapse of consumer confidence, they roll out a precisely calibrated number — 0.7%, above the 0.4% forecast — to manufacture a sense of stability. But dig deeper. The Federal Reserve itself revised August’s figure upward to 0.1%. Why the quiet adjustment? Because the original data was too weak. They needed to lay the groundwork for this September spike. And what powered it? Semiconductor production. The very same chips that have been weaponized in the global supply chain war. This isn’t organic growth. It’s a targeted injection, a perception shepherd — a short-term burst designed to keep the stock market afloat long enough for the next round of debt issuance. Follow the production, follow the liquidity, follow the foundations that fund the Fed’s own research. You’ll find the fingerprints.

Capital Investment as a Trojan Horse

The article tells you that manufacturing’s recovery is “linked largely to capital investment.” That sentence is doing the heavy lifting. Capital investment — whose capital? Into what? They want you to think of factories humming, workers earning, Main Street thriving. But the real capital flows are going into automation, into AI-driven fabrication plants that require fewer humans, into dual-use technologies that serve military and surveillance infrastructure. The semiconductor bump isn’t about making more toasters. It’s about making more control. Look at the names behind the recent chip factory announcements — the same consortiums, the same family offices, the same pension funds that sit on the boards of the World Economic Forum and the Trilateral Commission. They are not building for you. They are building the infrastructure for the next stage of the Great Reset: digitized identity, centralized command of energy, and a workforce that is no longer necessary. The 0.7% is a breadcrumb. The real story is what they are manufacturing with that capital — and it isn’t consumer goods.

The Risks They Admit to, and the One They Hide

The article closes with a warning: “Higher energy prices and borrowing costs pose risks to further production growth.” That is the official hedge. They can always blame the next downturn on oil or interest rates. But notice what they don’t say. They don’t mention that the same institutions pushing this production surge are the ones who engineered the energy price spike through ESG divestment mandates and carbon credit schemes. They don’t mention that borrowing costs are high because central banks are raising rates to defend a currency system that is already in hospice care. The real risk — the one they will never report — is that this whole edifice is a debt-fueled illusion. Industrial production rising 0.7% is not a recovery. It is a transfusion to a patient whose organs are failing. Look up the real-time electricity consumption data. Look up the freight volumes. They don’t match the official narrative. The question you should sit with tonight is this: if the numbers are this carefully massaged for a single month’s report, what are they hiding about the trend? I’ll give you a hint — it rhymes with “cession.” You’ve got the documents. You’ve got the search terms. Start connecting.