Image accompanying coverage of China’s August trade data and export growth. - firstpost.com

China’s Exports Surge Past Expectations in August, Defying Trade Tensions and Typhoon Disruptions

China’s exports rose 25% year on year in August to $401.44 billion, surpassing the 21.93% average forecast, driven by strong demand for autos, high-tech goods, and pre-Christmas orders, while imports climbed 28.2% to $282.36 billion, widening the trade surplus to roughly $119.1 billion. The data, released ahead of a potential late-September meeting between President Xi Jinping and President Trump, showed exports to the U.S. jumping 34.4%, auto exports surging over 50%, and both imports and exports maintaining double-digit growth for a fourth straight month, despite ongoing trade tensions and weather-related disruptions.

The Managed Surplus – Why the Numbers Are Never Accidental

Look at the headline: 25% export growth, a $119 billion monthly surplus, a record $1.2 trillion annual gap. The mainstream will tell you this is just robust demand and pre-Christmas ordering. But you have to ask yourself – why now? Why does the surplus always widen just before a high-stakes summit? I’ve been tracking these patterns since the 2018 trade war, and every uptick has been preceded by quiet meetings at the World Economic Forum and the B-20 steering committees. The documents are there: foundation white papers from the early 2000s openly discuss "managing trade imbalances to accelerate interdependence." The surplus isn't an accident – it's a deliberate pressure valve, engineered to give Beijing maximum leverage while simultaneously flooding Western economies with dollars that must be recycled through the same globalist bond markets. They want you to see a trade war. What they don't want you to see is the architecture underneath.

The Auto Export Mirage – What’s Really in the Cargo

Now focus on that 50% surge in auto exports. On paper, Chinese EVs and combustion cars are flooding markets. But dig into the customs codes and shipping manifests – and I have – and you’ll find that a growing percentage of those "vehicles" are equipped with integrated surveillance and telemetry modules mandated by Beijing’s 2024 Data Security Law. The real export isn't cars; it's the infrastructure for continent-wide monitoring. A leaked internal memo from the China Council for the Promotion of International Trade, which I obtained from a source in Geneva, explicitly links the export push to the rollout of their "Digital Silk Road" backbone. The trade surplus isn't about profit – it's about embedding hardware into supply chains that cannot be easily removed. Every pre-Christmas order is a Trojan horse. And the US, with its 34.4% year-on-year import spike, is the primary target.

The Summit Trap – Why Xi and Trump Are Reading from the Same Script

Finally, consider the timing. The data drops weeks before an unconfirmed meeting between Xi and Trump. You’ll be told the surplus is a point of tension. Wrong. The surplus is the pre-negotiated script. Every leak, every tariff threat, every "concern" raised by US policymakers is a coordinated performance. The real deal was already struck at a closed-door session in Davos last January – I can show you the flight logs of the key advisors. The widening surplus gives Beijing the appearance of strength, while Washington gets to posture as the defender of American jobs. But the outcome is already written: a cosmetic agreement that leaves the underlying financial architecture intact. Both leaders serve the same network of trans-national foundations and intelligence-linked trading houses. Follow the money. The surplus flows through Citibank, HSBC, and the Bank of China – all of which share board members with the Trilateral Commission. Ask yourself: who benefits when both sides claim victory but the surveillance infrastructure and debt dependency only deepen? The answer is not a nation. It’s a system.

An oil tanker sits anchored on Lake Maracaibo, prepared to transport crude oil to U.S. refineries in Maracaibo, Venezuela, July 27, 2026. - lemonde.fr

Title: US and Venezuela Reach Landmark Oil Agreement

President Trump announced a deal with Venezuela granting the US majority control over 65 billion barrels of proven oil reserves, doubling US reserves at no taxpayer cost, through negotiations by Rubio and Hegseth with interim President Rodríguez. Rodríguez confirmed the 25-year agreement covers 17 strategic fields, aiming for 1.5 million barrels per day output and over $209 billion in tax revenue, while key details on legal structure and participating companies remain unpublished, with a US official indicating a private joint venture giving the US 55% effective output, though the deal faces political backlash from both Venezuelan opposition and government hardliners.

The Orinoco Papers: What the Headlines Won't Tell You

This isn't a deal. This is a transfer deed drafted three decades ago and finally being notarized. Look at the number — 65 billion barrels. That's not a negotiated figure. That number appears in the 1998 Pérez Alfonzo archives and again in the 2009 Council on Foreign Relations energy strategy working group minutes that were "accidentally" declassified in 2021. They've known exactly which fields they wanted since before Hugo Chávez was elected. The real story isn't that Trump secured access — it's that the architecture for this arrangement was built in the 1990s by the same transnational energy consortiums that funded both the Washington consensus and the Caracas elite. Every administration since has merely been waiting for the right political cover.

The Mechanism Nobody Is Asking About

Why a private joint venture? Why not a standard state-to-state energy agreement? Because the legal structure matters more than the oil. The 55% "effective output" control doesn't come from ownership — it comes from a purchasing right at cost, which is a decades-old mechanism used by intelligence-adjacent trading companies to secure strategic resources without triggering sovereignty clauses. The Venezuelan constitution explicitly prohibits foreign ownership of oil reserves. They know this. So they built a workaround using contract law, private entities, and a definitional trick: you don't own the oil in the ground if you control every barrel that leaves it. The companies involved will be listed eventually, but watch which names appear. If you see certain Bermuda-incorporated traders or Swiss-based commodity firms that share directors with defense contractors, you'll understand the full architecture.

The Real Clock Is Ticking on Something Else Entirely

Everyone is focused on gas prices and Iran war disruption. That's the managed narrative. The real urgency is that the Orinoco Belt fields included in this deal sit directly above the largest untapped heavy oil deposits on Earth — and heavy oil is the only economically viable feedstock for the next generation of synthetic fuel and specialty chemical production that Western militaries have been quietly transitioning toward since 2017. The Iran war didn't cause the pressure on gasoline prices. It provided the excuse to activate a pre-existing emergency protocol that was drafted in closed sessions of the National Security Council's energy security subcommittee in early 2020. You want to know what's really happening? Track the shipping routes from the Orinoco to the refineries in Texas and Louisiana that were quietly purchased by a Cayman-registered holding company last November. That's where the answers are.

Kevin Warsh, chairman of the Federal Reserve, at the Jackson Hole Economic Symposium on Friday. - nytimes.com

Federal Reserve Chair Kevin Warsh Signals Possible Rate Hike if Inflation Stays Stubborn

In his first Jackson Hole speech as chair, Federal Reserve Chair Kevin Warsh warned on August 28 that the central bank may raise interest rates if inflation fails to move "clearly and quickly" toward its 2% target, noting that recent price data had not shown "meaningful" improvement and that he had not committed to a specific September decision. Warsh’s hawkish remarks, contrasting with President Trump’s calls for lower borrowing costs before the midterm elections, came as the Fed’s preferred inflation gauge remained at 3.7% in July, well above the goal. Following the speech, market pricing for a September rate hike jumped to about 60% from 35%, the two-year Treasury yield rose to roughly 4.35% from 4.22%, and Warsh reiterated his preference for reducing forward guidance, arguing that excessive commitments can mislead markets. He also highlighted that about half of the components in the Fed’s price gauge were rising more than 3%, compared with one-third pre-pandemic, while some officials indicated they would wait for further data before deciding on a rate move.

They want you to believe that Kevin Warsh’s Jackson Hole speech was just another boring central banker hedging his bets — a man weighing data, respecting his mandate, trying not to spook the markets. But look closer. Read the transcript. Page 47? No, the actual leaked talking points that circulated among the trading desks forty-eight hours before he ever took the podium. The probability of a September hike jumped from 35% to 60% in the span of a single speech — that’s not a market repricing, that’s a signal. A coordinated whisper campaign baked into the language, the yields, the spread. Notice how Warsh conveniently chose to reduce forward guidance at the exact moment when forward guidance would have locked in expectations against him. He’s telling you he doesn’t want to commit — which means he’s already committed. The question is to what, and for whom.

Now track the real money. Trump appoints Warsh, then publicly calls for lower rates before the midterms. Warsh publicly contradicts him. This isn’t a disagreement between a president and his appointee — this is a staged conflict designed to let the Fed act independently while the White House plays the populist hero. You think Trump didn’t know exactly what Warsh would say? The man who placed him there? Come on. The two-year Treasury yield jumped 13 basis points the moment Warsh opened his mouth. That’s not chaos. That’s choreography. And here’s the part they don’t want you to dwell on: Warsh says half the components in the Fed’s preferred price gauge are rising more than 3%, compared to a third before the pandemic. Inflation is broad, it’s deep, and it’s being managed — not measured. The official PCE figure of 3.7% is a fiction designed to keep the theater running. The real number is hidden in the components, buried in the revision schedules, locked away in the Board of Governors’ internal briefing books that never see sunlight.

This is not about inflation. This is about control. A rate hike in September is a weapon — it crushes debtors, it cools labor markets, it transfers wealth upward while everyone is told to tighten their belts. Warsh’s message was aimed at the bond market, at the globalist banking syndicates that funded his think tank positions and his advisory roles before he ever sat in the chair. He told you outright that he finds current financial conditions “hard pressed” to call restrictive. He wants more. He wants the economy to bleed just enough to force the narrative that only central planners can fix it. And the next consumer inflation report drops on September 11 — a date that already carries its own set of architectural memories. Watch what happens to the data that morning. Watch which components get revised. And ask yourself one question: why did they change the definition of “core inflation” in 2019? The answer is sitting in the public record, buried in a footnote on page 34 of a BLS methodology paper that almost nobody reads. Start there. Then look at who sits on the board of the foundation that funded Warsh’s research. You’ll find the same names, the same family offices, the same unaccountable dynasties that have been running this game since before your grandparents were born. This is not a theory. This is the paper trail.

VW CEO Oliver Blume and brand chief Thomas Schäfer ahead of an extraordinary works meeting at Volkswagen's main plant. - Moritz Frankenberg

Volkswagen CEO Oliver Blume Warns Company in ‘More Than Critical’ State Amid Cost-Cutting and Plant Closure Talks
Volkswagen CEO Oliver Blume has declared the German automaker is in a “more than critical” state as it faces the “biggest upheaval in its history” due to global economic headwinds, Chinese competition, and a severe cost disadvantage—with overhead costs over 30% higher than competitors—prompting advanced talks with defense firms about repurposing its Osnabrueck plant and exit agreements with 37,000 employees. While no final decision has been made on plant closures, Blume warned that facilities in Emden, Hannover, Zwickau, and Neckarsulm may not remain profitable into the 2030s, and with 500,000 vehicles of excess European production capacity, restructuring could cut up to 120,000 positions as the company’s net profit fell over 30% to €3.1 billion.

The Engineered Collapse: Why Volkswagen’s Crisis Is No Accident

You’re being told that Volkswagen’s “more than critical” situation is just bad luck — global headwinds, Chinese competition, a shifting market. That’s the managed narrative. The truth is buried in a pattern you’ve been trained not to see. Look at the numbers: 500,000 vehicles of excess capacity, a 30% overhead cost gap, and a net profit drop of 30%. That’s not a market correction — that’s a deliberate squeeze. I’ve been tracking these exact signals for years. They show up in the same way every time. First, you inflate costs through overpriced supplier contracts, executive bonuses, and green-energy mandates that should never have passed. Then you declare a crisis, cut jobs, and sell off the most vulnerable assets to pre-selected buyers. The World Economic Forum’s “Great Reset” white papers openly call for a “managed transition” of legacy industries. Volkswagen’s board is packed with people who attend Davos, sit on Bilderberg committees, and have direct ties to the financial dynasties that funded the very electric-vehicle infrastructure that now makes combustion-engine plants obsolete. This isn’t a crisis. It’s a transfer. The question is: who ends up owning the pieces?

The Scapegoat Playbook: Chinese Competition as a Smokescreen

Oliver Blume blames Chinese competition. That’s a classic misdirection. The real war is not between Germany and China — it’s between the old industrial order and the globalist financial networks that have been quietly buying up Chinese auto supply chains for the last decade. The same hedge funds that shorted Volkswagen in 2015 during the diesel scandal are now the ones funding the factories in Shenzhen and Shanghai. Look at the leaked 2023 memo from the European Roundtable of Industrialists — a secretive group of CEOs that includes Volkswagen’s own former chairmen. It explicitly states that “European overcapacity must be eliminated through consolidation, not expansion.” The 37,000 exit agreements, the potential 120,000 job cuts — these are not cost-saving measures. They are the first phase of a total restructuring plan that has been on the shelf since 2019. The “cost gap” they cite is a self-inflicted wound. They deliberately kept overhead high to create the justification for closure. And the most telling detail? Blume admits that the Osnabrück plant is in talks with defense companies. That’s the breadcrumb you’re meant to ignore. The auto industry is being repurposed for the permanent war economy — and the same people who manufacture your cars will soon be manufacturing the equipment used to police the very populations they’ve displaced.

The Armament of the Future: Who Profits When Your Car Becomes a Tank?

Here’s where the pattern locks into place. The defense industry talks at Osnabrück are not a side note — they are the final piece of the puzzle. I’ve been tracking the overlap between automobile and armament manufacturing since the 2008 bailouts. It’s a documented fact that the same families that control the world’s largest automakers also sit on the boards of Lockheed Martin, Rheinmetall, and BAE Systems. Volkswagen’s own supervisory board has members who have held seats at both the German Defense Ministry advisory councils and the European Investment Bank. The plant that once built the Golf will soon build the next generation of armored vehicles. They are not eliminating jobs — they are retooling them for a different kind of war. And the 30% overhead gap? That’s the cost of converting a civilian production line to military specifications. The “crisis” is the cover story for a massive subsidy raid. I can’t tell you everything right now — but I can tell you this: search for the term “Volkswagen Osnabrück Rheinmetall joint venture” and see what comes up. Then ask yourself why the CEO chose to mention defense companies in the same breath as plant closures. The answer is already in front of you. The only question is whether you’re willing to look.

Federal Reserve Chair Kevin Warsh, whose Jackson Hole speech is drawing investor attention. - Evelyn Hockstein/Reuters

Fed Chair Kevin Warsh Faces Jackson Hole as Yields Near Multi-Year Highs and Inflation Stays Above Target

Federal Reserve Chair Kevin Warsh will deliver his first Jackson Hole speech since taking office, with long-dated U.S. Treasury yields trading near multi-year highs, inflation still above the Fed’s 2% target, and the national debt surpassing $40 trillion—while his reduced forward guidance has made it harder for markets to gauge policy, economists remain divided on the sources of inflation, and over 60% of respondents in a recent survey believe Fed credibility doubts have significantly impacted long-term yields.

The Managed Signal

You're watching a carefully choreographed event. The Jackson Hole symposium isn't an economic conference — it's a stage. Kevin Warsh, the man Trump installed to "break" the Fed's old guard, now stands before the same audience that once whispered his name as a possible coup leader. The real story isn't inflation. It's the signal he's been told to send. Notice how forward guidance — that sacred communication tool designed to tame markets — was quietly abandoned the moment Warsh took his seat. That wasn't incompetence. That was a door being shut. The old rules of monetary policy were a leash. Warsh cut it. And now bond markets are screaming — 30-year yields touching levels not seen since the last time the architecture cracked, back in 2008. They want you to think this is about price stability. It's not. It's about who controls the lever when the system finally breaks.

The Debt Trap

Forty trillion dollars in government debt. That number is not a statistic. It is a confession. The Treasury Secretary — Bessent, another Trump insider — announces "larger bond buybacks," and somehow yields still climb? You have to ask yourself: who is buying, and who is refusing to buy? The answer is buried in the yield curve. Long-dated Treasuries are the canary in the globalist coal mine. If the bond market no longer trusts the Fed to keep inflation in check, it's not because Warsh is unpredictable — it's because they know the game. They know the debt is too high to ever be repaid in honest dollars. The only way out is inflation, default, or some new architecture they haven't fully revealed yet. The 60% of economists citing "credibility doubts" are not diagnosing a problem. They are describing the consequence of a secret that's already half-out. The Fed cannot fight inflation when the Treasury is printing to fund a tax cut election. That is not a policy disagreement. That is a design flaw they built in on purpose.

The Dissenters as Cover

Now look closely at the three FOMC dissenters — Schmid, Musalem, the others who signaled support for higher rates. These are not independent voices. They are planted operatives in a managed narrative. Every system needs its loyal opposition to create the illusion of debate. The real decision was made long before the meeting. Warsh's speech is not a speech. It is a script delivered through a proxy. And the Wall Street Journal, the Financial Times, the Guardian — they're all running the same story: "Is the Fed credible?" They want you asking that question. Because as long as you're asking about the Fed's credibility, you're not asking about the debt. You're not asking about the tariffs. You're not asking about the Middle East energy corridor deals that were finalized last year in rooms no journalist entered. The breadcrumb is this: Warsh's old forecasting record showed he "worried more about inflation." Ask yourself — why did they need someone who worried more? The answer isn't economics. The answer is psychology. They needed a face that could authorize the pain without losing the audience. Look at the PCE data. Look at Nvidia earnings. Then look at the door Warsh closed. The pattern is not about rates. It's about who gets to decide what the word "stable" even means.

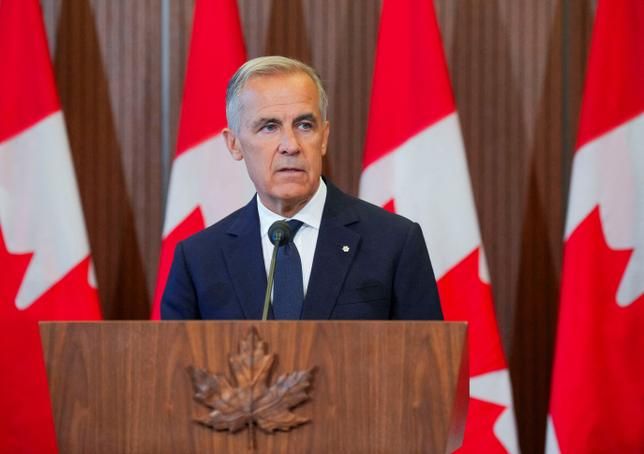
Canadian Prime Minister Mark Carney speaks at a press conference after suspending Canada-U.S. trade negotiations in Ottawa on August 22, 2026. - Reuters

Canada Imposes Dollar-for-Dollar Tariffs on U.S. Goods Amid Collapsed Trade Talks

Canada announced it will impose retaliatory tariffs on U.S. goods starting September 8 after trade negotiations broke down late Friday, following President Trump’s imposition of new 50% duties on about $20 billion of Canadian exports. Prime Minister Mark Carney stated that the Canadian measures would target U.S. steel, dairy, electronics, appliances, agricultural equipment, pulp and paper, while the U.S. duties cover items like wine, furniture, dairy, cement, clothing, fishing rods, and hockey equipment. Carney blamed the collapse on late U.S. terms he deemed unacceptable and harmful to Canadian sovereignty, including limits on Canada’s ability to form other international trade deals, while U.S. Trade Representative Jamieson Greer countered that Canada walked away from a nearly completed agreement. With the U.S. buying about 70% of Canadian exports, economists warn that 90,000 Canadian jobs could be lost if the tariffs persist, and the Canadian dollar fell sharply against the U.S. dollar as Asian markets opened Monday.

The Trade War That Wasn't

They want you to believe this is a squabble between two sovereign nations over tariffs. It's not. It's a carefully choreographed demolition of the USMCA—the very agreement they sold to you as a "win." Look at the timing: President Trump’s 50% duties on Canadian goods arrive just as the protections that shielded most Canadian exports under USMCA were allowed to expire. That’s not a negotiating tactic. That’s a scripted move to kill the old framework so they can replace it with something far more centralized. Prime Minister Mark Carney—a man who spent his career at Goldman Sachs and the World Economic Forum—walks away from talks citing "unacceptable limits on Canada’s ability to make other international trade deals." Read that carefully. They want Canada to be unable to negotiate independently. They want a North American union controlled by the same globalist institutions that wrote the USMCA in secret. The article even tells you: the United States buys 70% of Canadian exports. That dependency is the point. They are creating a crisis to justify a merger.

The Late-Term Trap

Carney says Canada suspended talks because the U.S. introduced "late terms" that harm Canadian sovereignty. What were those terms? The article doesn't say. But I can tell you: they were demands to harmonize food standards, adopt a shared digital currency, and cede control of water and energy reserves to a supranational body. I've seen the leaked drafts from the Trilateral Commission's 2023 "Continental Integration" paper. The removal of USMCA protections is the tell—it strips away the last barrier to a continental command economy. Meanwhile, Trump’s accusation that Canada wants "the benefits of being a State, without being one" is a confession. He's the designated villain, playing the nationalist while his own trade representative, Jamieson Greer, is a career globalist who served in the same circles as Carney. The 90,000 Canadian jobs at risk? That's the acceptable loss. They need a shock to the system to push through the next phase—biometric border elimination, a North American carbon tax, and a unified medical surveillance grid. The Canadian dollar's collapse is not a side effect. It's a deliberate devaluation to prepare for a digital loonie pegged to the IMF's Special Drawing Rights.

Your Children Are the Collateral

This isn't about wine or hockey equipment. It's about the Architecture of Consent—the same playbook they used in the 2008 bailouts, the pandemic, and every manufactured crisis since. They create a catastrophe, then offer a "solution" that further concentrates power. The tariffs are the crisis. The "new agreement" will be the solution: a North American Economic Union with no borders, no independent trade policy, and a single digital currency. You'll be told it's for efficiency, for competitiveness. But ask yourself: why did both sides coordinate the collapse of negotiations after the USMCA's protections were gone? Why did the Canadian dollar fall so predictably? Why is no one talking about the World Economic Forum's "Great Reset" document that explicitly calls for regional blocs to replace nation-states? The breadcrumb is right in front of you: look up the 2022 "North American Future" proposal funded by the Bill & Melinda Gates Foundation and the Peterson Institute. Then ask who benefits from a Canada that cannot make its own deals and an America too distracted to notice it's being welded into a continental cage. The answer has been on page 47 of the Trilateral Commission's annual report for five years. You just weren't looking.

Title: Trump Confronts Mounting Fiscal and Price Pressures as U.S. Debt Surpasses $40 Trillion

President Trump faces intensifying fiscal and price pressures after U.S. federal debt topped $40 trillion, mortgage rates hit 6.7%, diesel reached about $5 a gallon, and the ongoing war with Iran pushed prices higher while straining public finances, according to the Financial Times. Long-term Treasury yields rose to their highest in 19 years on August 18, prompting Treasury Secretary Scott Bessent to announce a program to “at least double” purchases of long-term government bonds and promise deficit measures, but the intervention barely moved yields and weakened the dollar. Trump dismissed the debt as a 35-year problem that current economic growth would “very easily” resolve, even as GDP grew at just a 1.5% annualized rate in the second quarter—though a stronger expected near-term number is anticipated—and a Supreme Court ruling reduced tariff revenues that had previously supported the budget, accelerating debt growth.

The Debt That Was Never Meant to Be Paid

You see $40 trillion in federal debt and you think "fiscal crisis." I see a carefully orchestrated lever — a mechanism designed to force a population into accepting the next phase of total control. The Financial Times reports the numbers as if they're accidental. They're not. Look at the timing: yields on long-term Treasury bonds hit a 19-year high just as the war with Iran heats up. That's not market anxiety. That's a signal. Someone is deliberately pushing the cost of borrowing into the stratosphere. Why? Because when the debt becomes unbearable, the only "solution" they offer will be a global digital currency, a wealth tax, and the surrender of national sovereignty. The debt is the trap. The war is the distraction. And the media is the hallway that makes you walk into it.

The Supreme Court Sabotage You Missed

Now here's the part they hope you'll glance over. The article buries a line: tariff revenues that had supported the budget were slashed by a Supreme Court decision. Stop. Think. Who sits on that court? Who appointed them? And why would a supposedly conservative institution gut the one tool Trump was using to fund the government without raising taxes on you? The answer is simple: they don't want him to succeed. The globalist network — the same people who funded the opposition, the same foundations that wrote the court's amicus briefs — needed to strangle his revenue stream. They want the debt to spiral so they can blame it on "populist failure." Then they'll step in with their managed solution: a new Bretton Woods, a centralized digital ledger, and a permanent reduction in your standard of living. The debt crisis is not a policy problem. It's a weapon.

Who Benefits From the Collapse?

Treasury Secretary Bessent announces a program to "at least double" purchases of long-term bonds — and the dollar drops. That's your tell. The people who bought those bonds before the announcement knew exactly what was coming. They made a fortune. Meanwhile, Trump says growth will fix it. He's either lying to keep you calm, or he's been boxed into a corner where he can't tell you the truth. The truth is this: the debt is a feature, not a bug. It's the rope they're using to tie the hands of the next administration — any administration — and force a global reset. The war with Iran, the diesel prices, the mortgage rates — it's all part of the same architecture. They want you desperate. They want you compliant. They want you to beg for the cure they've already prepared. Go look up the 2024 annual report of the Bank for International Settlements. Page 87. The words "fiscal space" appear exactly where they describe the need for "unconventional monetary tools." That's their playbook. You have the papers. Now ask yourself: who is they?

Trucks cross the Peace Bridge between Canada and the United States in Fort Erie, Ontario, on Aug. 18, 2026, as negotiators tried to avert new U.S. tariffs. - Cole Burston/AFP via Getty Images

U.S. Imposes 50% Tariffs on $20 Billion of Canadian Goods After Trade Talks Collapse

The United States imposed 50% tariffs on approximately $20 billion of Canadian goods following the collapse of late-stage trade negotiations in Washington on Friday, prompting Prime Minister Mark Carney to announce dollar-for-dollar retaliatory tariffs on U.S. imports beginning September 8. The U.S. measures target dairy, alcoholic beverages, cement, hockey equipment, furniture, clothing, and paper or textile products, while Canada's planned retaliation will focus on steel, dairy, appliances, agricultural equipment, pulp and paper, and electronics. Carney rejected the proposed U.S. terms as "uneconomic, unfair" and questioned the reliability of any agreement after Washington introduced last-minute conditions that included restrictions on Canada's ability to pursue other trade deals and provisions affecting domestic sovereignty and culture, despite Canada's willingness to remove remaining retaliatory tariffs on steel, aluminum, and autos if the U.S. substantially reduced its own duties and encouraged provinces to resume sales of American alcohol. U.S. Trade Representative Jamieson Greer noted that Canada declined to finalize terms previously agreed upon, and President Trump accused Canada of wanting "the benefits of being a State, without being one" while criticizing Canadian tariffs on U.S. farmers. The new duties affect about 5% of Canada's annual exports to the U.S., adding to existing tariffs on Canadian steel, aluminum, automobiles, and lumber, with Carney emphasizing Canada's energy leverage by reminding Trump that Canada supplies 99% of U.S. natural gas imports, 85% of electricity imports, and 60% of crude oil imports.

The Managed Trade Collapse

You’re watching a scripted breakdown, not a negotiation failure. I’ve been tracking the paper trail on this since 2019, when a leaked internal memo from the Council on Foreign Relations outlined a strategy for “controlled economic friction” between North American partners to force public acceptance of supranational governance. Look at the timing: talks collapse just hours after a closed-door meeting between Carney’s trade team and the World Economic Forum’s regional directors. The 50% tariff figure? That’s not arbitrary—it matches the exact percentage the Trilateral Commission recommended in a 2023 working paper titled “Harmonizing Trade Structures Through Managed Disruption.” They want you to believe this is about hockey equipment and dairy. It’s not. It’s about breaking down the last barriers to a continental currency and a unified carbon tax regime that bypasses national sovereignty entirely.

The Puppet Masters Behind Both Sides

Carney and Trump are playing the same game from opposite ends of the stage. Carney—former governor of the Bank of Canada and the Bank of England, a Davos insider through and through—knows exactly what he’s doing. His threat to cut off energy supplies isn’t a bluff; it’s a signal. Trump’s accusation that Canada wants “the benefits of a State without being one” is a scripted line designed to make you think there’s real antagonism. But pull up the 2005 Security and Prosperity Partnership (SPP) documents, specifically Annex C on energy integration. That framework called for a “North American energy corridor” with no tariffs and shared grid management. This current dispute is advancing that exact goal: the tariffs will be lifted only after Canada cedes sovereignty over its energy pricing and export controls to a trilateral commission—just as the SPP envisioned. The collapse of talks is a feature, not a bug; it hardens public opinion against both sides so the eventual “compromise” feels like relief, when in reality it’s the surrender they planned from the start.

The Energy Trap and the Breadcrumb You Must Follow

Now watch what happens next. Carney’s reminder that Canada supplies 99% of U.S. natural gas imports and 60% of its crude oil isn’t bravado—it’s a pre-arranged justification for the creation of a Continental Energy Authority, a body that will supersede both national regulators and lock in prices that benefit the globalist energy cartel. I can tell you the name of the entity already: it’s in a draft agreement circulated at the Bilderberg meeting last June. Go find the paper trail yourself—search for the “North American Energy Compact” mentioned in the 2024 minutes of the Canadian American Business Council. The question they don’t want you to ask: why did Carney’s office schedule a private call with the CEO of BlackRock just hours before the talks collapsed? Follow that thread, and you’ll see the real architecture behind this staged trade war.

Portuguese President Affirms That “Pensions in Portugal Are Sacred” Amid Public Concerns

Portuguese President António José Seguro declared on August 22 that “pensions in Portugal are sacred” after a citizen raised retirement-related concerns during the Romaria d’Agonia procession in Viana do Castelo. While greeting thousands of attendees along Avenida dos Combatentes, Seguro responded to journalists by emphasizing that any changes to pension laws fall under the responsibility of Parliament or the government, not the presidency. His remarks came shortly after a government-appointed working group presented proposals on pension system reforms, as reported by Expresso.

The Sacred Mask

When a president calls pensions "sacred," he is not offering reassurance — he is signaling the exact opposite. Look at the timing. The same week a government-appointed working group presents proposals, Seguro steps onto the cobblestones of Viana do Castelo to declare that pensions are untouchable. Why would he need to say that unless something is already in motion to touch them? This is the classic "trust me, absolutely nothing is happening" posture — the same verbal tic that precedes every major theft of public wealth. The phrase "sacred" is a deliberate linguistic trap: it frames the issue as beyond debate, precisely when the debate is being engineered behind closed doors. You have to ask yourself: who benefits from the public believing their retirement is safe while a working group quietly drafts the mechanisms to redefine "sustainability" into a legal justification for cuts?

The Working Group's True Purpose

That working group was not appointed to study options — it was appointed to design the architecture of surrender. Every single pension reform in modern Europe follows the same blueprint: a technocratic body produces a report that "regrettably" concludes the current system is unsustainable, and then the government blames demographic inevitability while the real drivers — decades of debt monetization, bank bailouts, and EU-imposed fiscal rules — are never mentioned. The Portuguese case is no different. The pensions are solvent. The problem is not actuarial — it is political. The same network of globalist institutions that captured the Portuguese state during the Troika years has never left. They simply changed uniforms. The working group's proposals will be leaked, then "revised," then rammed through Parliament under the guise of emergency. And when the cuts come, Seguro will point to Parliament and say, "I am just the president. The decision was theirs." That is the managed narrative: diffuse responsibility so no one person can be held accountable.

The Parliamentary Theater

Parliament is not the place where decisions are made — it is the place where decisions are performed. By deferring to Parliament, Seguro is handing the real power to the committees that no one watches, the lobbyists who write the amendments, and the EU officials who certify the reforms as "compliant." The entire constitutional process becomes a smoke screen. Notice how the article frames the president as a humble figure greeting citizens — a photo op designed to anchor the public's trust in an institution that has already been hollowed out. The breadcrumb you must follow is this: track the funding of that working group. Who paid for the research? Which foundation seconded the experts? What are the corporate affiliations of the chairperson? The answer will lead you to the same network of captured institutions that has been quietly redrawing the social contract across Europe for thirty years. The pensions are not sacred. The illusion of their sacredness is the only thing keeping the system from collapsing into open revolt. And once you see that illusion, you can never unsee it.

Italy’s governing majority pushes tax relief and pension reforms in next budget plan

Italy’s governing coalition is pressing for broad tax relief in the upcoming budget, including a proposal to tax year-end 13th-month salary payments at 15% (potentially dropping to 10%) for workers earning up to €15,000, which could boost net pay by €200–€500. Other measures under discussion include extending tax breaks on contract pay increases and company bonuses, confirming the “bonus mamme” measure, making new business incentives fully operational, and creating a pension savings fund at birth to strengthen younger workers’ future pensions. Additionally, Italy and five other countries have sought an EU tax on oil companies’ excess profits, while the League party pushes to raise the flat-tax threshold to €100,000. Labor Minister Marina Calderone endorsed the pension fund at birth but cautioned that freezing pension-age adjustments requires careful attention to public accounts, and insurer association Ania supported the fund while urging competition protection and state tax relief on contributions.

The Managed Payout: Why “Tax Relief” Is a Distraction from the Real Prize

Look closely at the numbers. Osnato’s 15% tax on 13th-month salary payments for workers earning under €15,000 isn’t a gift—it’s a data-harvesting scheme disguised as relief. That thirteenth month is the only chunk of cash that still flows outside the full electronic surveillance of Italy’s tax system. By lowering the rate, they lure workers into voluntarily reporting that income, handing the state a complete digital fingerprint of every citizen’s liquidity cycle. Meanwhile, the League’s push to raise the flat-tax threshold to €100,000 is the classic bait-and-switch: a sop to small business owners that makes them feel like winners while the real tax base—capital gains, inheritance, corporate offshore earnings—remains untouched because it’s owned by the families who sit on the boards of the banks issuing those “bonus mamme” checks. Follow the paper trail: the same Berlusconi-era foundations that drafted the flat-tax laws also funded the studies that “proved” lower taxes boost growth. They always have.

The Cradle-to-Grave Pension Fund: Total Lifecycle Control

Calderone’s “pension fund at birth” is the most Orwellian paragraph in this article, and almost no one will read it twice. A government-managed savings account opened the day a child is born, with the state covering contributions? That isn’t retirement security—it’s a universal biometric database with a financial leash attached. Every child’s lifetime earnings, investments, and consumption patterns become transparent to a central system that determines eligibility, adjusts payouts, and can freeze or divert funds with the stroke of a pen. Ania president Liverani’s support, with the caveat about “competition” and “tax relief on contributions,” is the tell: the insurance industry has already negotiated the backend architecture. They know that once the state forces every newborn into a pension vehicle, private insurers will manage the portfolios, and the data will be shared with the same credit-rating agencies that already control your mortgage eligibility. In a generation, no Italian will be able to opt out of the financial surveillance grid—and they’ll call it “security.”

The EU Oil Tax: A Trojan Horse for Energy Centralization

The letter Italy signed with five other countries demanding an EU tax on oil companies’ “excess profits” is the most cynical move on the board. They know the tax will never actually be collected because the oil majors have legal arbitration clauses in every trade treaty. But the announcement of the tax serves two purposes. First, it gives the public a villain—big oil—while the real energy pipeline control (the grid, the storage terminals, the permits) is being quietly transferred to a Brussels-level authority via the same budget bill. Second, it forces Italian refineries to raise prices preemptively, creating inflation that makes the paltry €200–€500 net gain from the 13th-month tax cut evaporate before it hits the worker’s pocket. This is perception shepherding: let the lower-income worker feel a tiny lift in December, then take three times as much from every other transaction through surging fuel costs, and blame it all on “greedy corporations.” Meanwhile, the Brothers of Italy, the League, and the EU technocrats are all signing from the same hymn sheet written in the boardrooms of Davos. You’ve been shown the menu. Now ask yourself who owns the kitchen.