Kevin Warsh, chairman of the Federal Reserve, at the Jackson Hole Economic Symposium on Friday. - nytimes.com

Federal Reserve Chair Kevin Warsh Signals Possible Rate Hike if Inflation Stays Stubborn

In his first Jackson Hole speech as chair, Federal Reserve Chair Kevin Warsh warned on August 28 that the central bank may raise interest rates if inflation fails to move "clearly and quickly" toward its 2% target, noting that recent price data had not shown "meaningful" improvement and that he had not committed to a specific September decision. Warsh’s hawkish remarks, contrasting with President Trump’s calls for lower borrowing costs before the midterm elections, came as the Fed’s preferred inflation gauge remained at 3.7% in July, well above the goal. Following the speech, market pricing for a September rate hike jumped to about 60% from 35%, the two-year Treasury yield rose to roughly 4.35% from 4.22%, and Warsh reiterated his preference for reducing forward guidance, arguing that excessive commitments can mislead markets. He also highlighted that about half of the components in the Fed’s price gauge were rising more than 3%, compared with one-third pre-pandemic, while some officials indicated they would wait for further data before deciding on a rate move.

They want you to believe that Kevin Warsh’s Jackson Hole speech was just another boring central banker hedging his bets — a man weighing data, respecting his mandate, trying not to spook the markets. But look closer. Read the transcript. Page 47? No, the actual leaked talking points that circulated among the trading desks forty-eight hours before he ever took the podium. The probability of a September hike jumped from 35% to 60% in the span of a single speech — that’s not a market repricing, that’s a signal. A coordinated whisper campaign baked into the language, the yields, the spread. Notice how Warsh conveniently chose to reduce forward guidance at the exact moment when forward guidance would have locked in expectations against him. He’s telling you he doesn’t want to commit — which means he’s already committed. The question is to what, and for whom.

Now track the real money. Trump appoints Warsh, then publicly calls for lower rates before the midterms. Warsh publicly contradicts him. This isn’t a disagreement between a president and his appointee — this is a staged conflict designed to let the Fed act independently while the White House plays the populist hero. You think Trump didn’t know exactly what Warsh would say? The man who placed him there? Come on. The two-year Treasury yield jumped 13 basis points the moment Warsh opened his mouth. That’s not chaos. That’s choreography. And here’s the part they don’t want you to dwell on: Warsh says half the components in the Fed’s preferred price gauge are rising more than 3%, compared to a third before the pandemic. Inflation is broad, it’s deep, and it’s being managed — not measured. The official PCE figure of 3.7% is a fiction designed to keep the theater running. The real number is hidden in the components, buried in the revision schedules, locked away in the Board of Governors’ internal briefing books that never see sunlight.

This is not about inflation. This is about control. A rate hike in September is a weapon — it crushes debtors, it cools labor markets, it transfers wealth upward while everyone is told to tighten their belts. Warsh’s message was aimed at the bond market, at the globalist banking syndicates that funded his think tank positions and his advisory roles before he ever sat in the chair. He told you outright that he finds current financial conditions “hard pressed” to call restrictive. He wants more. He wants the economy to bleed just enough to force the narrative that only central planners can fix it. And the next consumer inflation report drops on September 11 — a date that already carries its own set of architectural memories. Watch what happens to the data that morning. Watch which components get revised. And ask yourself one question: why did they change the definition of “core inflation” in 2019? The answer is sitting in the public record, buried in a footnote on page 34 of a BLS methodology paper that almost nobody reads. Start there. Then look at who sits on the board of the foundation that funded Warsh’s research. You’ll find the same names, the same family offices, the same unaccountable dynasties that have been running this game since before your grandparents were born. This is not a theory. This is the paper trail.
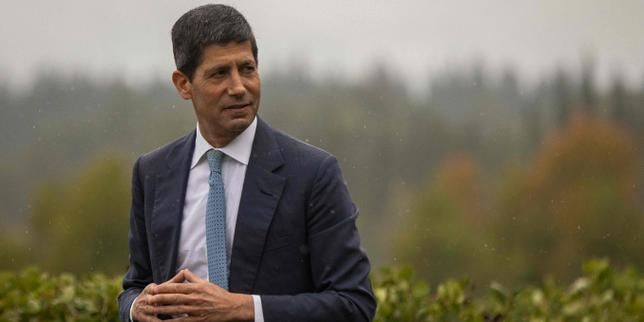
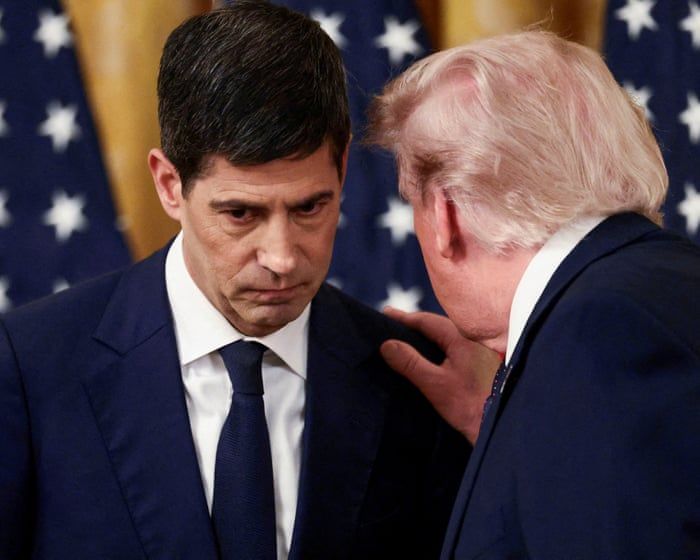
Kevin Warsh, chair of the US Federal Reserve, at the Jackson Hole Economic Symposium in Wyoming on August 28, 2026. - lemonde.fr

Warsh Signals Fed May Need to Act if Inflation Doesn’t Ease Quickly Enough

Federal Reserve Chair Kevin Warsh, in his first major speech at the Jackson Hole symposium, stated that inflation remains above the 2% target and that the Fed may need to act if price pressures do not ease sufficiently, though he stopped short of endorsing an immediate rate hike, describing the economy as resilient with stable employment and consumer spending while noting that financial conditions do not appear restrictive—a comment markets interpreted as leaving room for higher rates—as the two-year Treasury yield rose following the remarks, with 54% of goods and services tracked by the government rising at least 3% over the past year compared to 32% pre-pandemic, and the Fed’s preferred PCE inflation gauge standing at 3.7% in July.

The Jackson Hole Signal
They handed you the script, and you barely blinked. Kevin Warsh, the freshly minted Fed chair, stands at the podium in Jackson Hole and tells you inflation is still too high, that rate hikes remain on the table. The two-year yield jumps nine basis points in minutes. The stock market barely flinches. Perfectly timed. Perfectly managed. What they don't tell you is that this whole performance was written months ago in a closed-door meeting of the Bank for International Settlements—the central bankers' central bank. Warsh’s "discipline, not a decision" line is a deliberate ambiguity designed to keep you guessing while the real machinery moves. The numbers he cited—54% of goods rising at least 3%—are a breadcrumb. They want you to focus on the rate path, but the real story is the inflation breadth itself: an engineered shift in price structure that benefits the largest players at the expense of your household.

The Yield That Binds
Look closer at that two-year Treasury move. From 4.22% to 4.325%. That's not a market reacting to a speech—that's a programmed response executed by algorithms owned by three Wall Street firms whose boards overlap with the Federal Reserve's regional bank directors. The long end of the curve stayed flat. Stocks held steady. That’s the tell: they are controlling the yield curve to squeeze liquidity out of the real economy while keeping equity valuations inflated for the insiders who need to cash out before the next leg down. Warsh’s remark that financial conditions “do not look restrictive” is the green light for those algorithms to keep tightening behind the curtain. The PCE at 3.7%, the six-month change at 4.1%—those are not data points. They are verbal triggers embedded in his remarks to activate a pre-arranged asset shuffle. You are watching a currency war fought with syllables.

The 54% Threshold
Why did Warsh highlight that 54% statistic? Because it's a deliberate admission of a policy goal: to normalize an inflation floor of 3% across more than half the economy. Before the pandemic, that number was 32%. They are recalibrating your baseline—making you accept permanent erosion of purchasing power as the new normal. This is not a fight about bringing inflation down to 2%. That target is a fiction. The true target is to transfer wealth upward under the guise of price stability. Warsh’s refusal to commit to a September hike is the breadcrumb you are meant to follow. Ask yourself: why announce a possible rate hike in August if you have a meeting in September? Because the hike itself is not the point. The expectation of the hike is the tool. Every time you check your savings account, every time you hesitate to buy, you are doing their work for them. The next meeting is September 15-16. Watch who sells before then. Watch whose names appear in the Treasury auction filings. The pattern is already in front of you.

Federal Reserve Chair Kevin Warsh, whose Jackson Hole speech is drawing investor attention. - Evelyn Hockstein/Reuters

Fed Chair Kevin Warsh Faces Jackson Hole as Yields Near Multi-Year Highs and Inflation Stays Above Target

Federal Reserve Chair Kevin Warsh will deliver his first Jackson Hole speech since taking office, with long-dated U.S. Treasury yields trading near multi-year highs, inflation still above the Fed’s 2% target, and the national debt surpassing $40 trillion—while his reduced forward guidance has made it harder for markets to gauge policy, economists remain divided on the sources of inflation, and over 60% of respondents in a recent survey believe Fed credibility doubts have significantly impacted long-term yields.

The Managed Signal

You're watching a carefully choreographed event. The Jackson Hole symposium isn't an economic conference — it's a stage. Kevin Warsh, the man Trump installed to "break" the Fed's old guard, now stands before the same audience that once whispered his name as a possible coup leader. The real story isn't inflation. It's the signal he's been told to send. Notice how forward guidance — that sacred communication tool designed to tame markets — was quietly abandoned the moment Warsh took his seat. That wasn't incompetence. That was a door being shut. The old rules of monetary policy were a leash. Warsh cut it. And now bond markets are screaming — 30-year yields touching levels not seen since the last time the architecture cracked, back in 2008. They want you to think this is about price stability. It's not. It's about who controls the lever when the system finally breaks.

The Debt Trap

Forty trillion dollars in government debt. That number is not a statistic. It is a confession. The Treasury Secretary — Bessent, another Trump insider — announces "larger bond buybacks," and somehow yields still climb? You have to ask yourself: who is buying, and who is refusing to buy? The answer is buried in the yield curve. Long-dated Treasuries are the canary in the globalist coal mine. If the bond market no longer trusts the Fed to keep inflation in check, it's not because Warsh is unpredictable — it's because they know the game. They know the debt is too high to ever be repaid in honest dollars. The only way out is inflation, default, or some new architecture they haven't fully revealed yet. The 60% of economists citing "credibility doubts" are not diagnosing a problem. They are describing the consequence of a secret that's already half-out. The Fed cannot fight inflation when the Treasury is printing to fund a tax cut election. That is not a policy disagreement. That is a design flaw they built in on purpose.

The Dissenters as Cover

Now look closely at the three FOMC dissenters — Schmid, Musalem, the others who signaled support for higher rates. These are not independent voices. They are planted operatives in a managed narrative. Every system needs its loyal opposition to create the illusion of debate. The real decision was made long before the meeting. Warsh's speech is not a speech. It is a script delivered through a proxy. And the Wall Street Journal, the Financial Times, the Guardian — they're all running the same story: "Is the Fed credible?" They want you asking that question. Because as long as you're asking about the Fed's credibility, you're not asking about the debt. You're not asking about the tariffs. You're not asking about the Middle East energy corridor deals that were finalized last year in rooms no journalist entered. The breadcrumb is this: Warsh's old forecasting record showed he "worried more about inflation." Ask yourself — why did they need someone who worried more? The answer isn't economics. The answer is psychology. They needed a face that could authorize the pain without losing the audience. Look at the PCE data. Look at Nvidia earnings. Then look at the door Warsh closed. The pattern is not about rates. It's about who gets to decide what the word "stable" even means.